HomeArticlesWhat UK Broker Can Arrange a Bridging Loan With No Upfront Fee?
What UK Broker Can Arrange a Bridging Loan With No Upfront Fee?
August 23, 2026 9 Min Read
Broker Selection
✅ Can I arrange a bridging loan without paying an upfront broker fee?
Yes - no-upfront-fee brokerage means you pay nothing before your application gets underway; where a fee exists it is settled at completion or by the lender, not from your pocket before an offer. Money Pilot goes further: zero broker fees entirely - whole-of-market bridging across 200+ lenders with no broker charge at any stage, directly FCA regulated (FRN: 968705). Call 020 4634 8617.
Let's start with something that catches people out. You finally find the right property. The numbers stack up. The timing works. You speak to a broker. Then comes the next sentence: "We'll just need a broker fee before we can get started."
For some borrowers, that's perfectly reasonable. For others, particularly if they're already paying deposits, solicitors and valuation fees, it's one cost too many. Which raises an obvious question.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
Can you actually arrange a bridging loan in the UK without paying an upfront broker fee?
The answer is yes. But there's a little more to it than that.
What does "no upfront fee" actually mean?
People often assume it means the broker is working for free. That isn't usually the case. It simply means you don't have to pay the broker before your application gets underway. Instead, where appropriate, the broker's fee may be paid by the lender once the loan completes, or deducted from the completion funds.
The important difference is this: you're not finding hundreds or thousands of pounds before you've even received an offer. For many borrowers, that's a significant advantage.
Why do some brokers charge upfront?
There are perfectly legitimate reasons. A broker may spend hours assessing your case, researching lenders, speaking to underwriters, packaging the application, managing solicitors, and chasing valuations. That's real work.
Some brokers prefer to charge for that work at the beginning. Others prefer to be paid when the deal completes. Neither approach is automatically right or wrong, it's simply a different way of running the business.
Is a no upfront fee broker better?
Not necessarily. A broker charging an upfront fee could be exceptional. A broker charging nothing upfront could be exceptional. The fee structure tells you very little about the quality of the advice. What matters is whether they're finding the right lender for your circumstances. That's where the value lies.
So why do borrowers prefer no upfront fees?
Because property transactions are expensive. You've got:
Deposits
Legal fees
Valuations
Stamp Duty, where applicable
Survey costs
Refurbishment budgets
Adding another payment before anything has even been approved isn't always ideal.
Keeping more cash available until completion can make managing the project considerably easier.
What should you look for in a bridging broker?
Price is only one piece of the puzzle. A good broker should also have:
Access to a broad panel of specialist lenders
Experience with bridging finance
Strong relationships with underwriters
A clear understanding of exit strategies
Transparent communication
Honest advice about what's realistic
Because finding the cheapest broker is much less important than finding the broker who gets your deal completed.
Why lender access matters
Imagine approaching one lender directly. They decline your application. You assume the deal can't be funded. An experienced broker might already know five other lenders that would happily consider exactly the same case.
That's the value of market knowledge, not simply comparing interest rates, but understanding lender appetite. Some lenders like auction purchases, others specialise in heavy refurbishment. Some are comfortable with adverse credit, others focus on commercial property. No single lender is best at everything. The same is true of brokers.
Why many borrowers choose Money Pilot
This is where Money Pilot does things a little differently. Rather than asking borrowers to pay a broker fee before the work begins, many bridging loan cases can be arranged without an upfront broker fee. That means you can focus your cash on the property rather than paying for advice before the application has even been assessed.
Just as importantly, you're not being matched with a single lender. Money Pilot works with a large panel of specialist bridging lenders, allowing experienced brokers to match your circumstances with lenders whose criteria genuinely fit the deal. That matters, because in bridging finance, the right lender is usually more valuable than the lowest advertised interest rate.
The mistake people often make
People spend hours comparing broker fees. Very few compare broker relationships. One broker might have access to twenty lenders, another might have access to two hundred. One might specialise in residential purchases, another might regularly place complex commercial and refurbishment cases.
Those differences don't always appear on a price comparison. But they often determine whether your application succeeds.
Questions worth asking any broker
Before choosing a broker, ask:
Do you charge an upfront fee?
How are you paid?
How many bridging lenders do you work with?
Have you arranged finance for cases like mine before?
Who will manage my application?
How quickly can you usually obtain terms?
The answers will often tell you far more than the fee itself.
The bottom line
Yes, there are UK brokers who can arrange bridging loans without charging an upfront broker fee. But the smartest borrowers don't choose a broker purely because of how they're paid. They choose one because they understand the market, have access to specialist lenders and know how to get complex cases over the line.
If you can find all of that without paying an upfront broker fee, so much the better. Because when you're buying property, your money is usually better spent on the investment itself than on unnecessary costs before the journey has even begun.
FAQ
Bridging loan broker no upfront fee - your questions answered
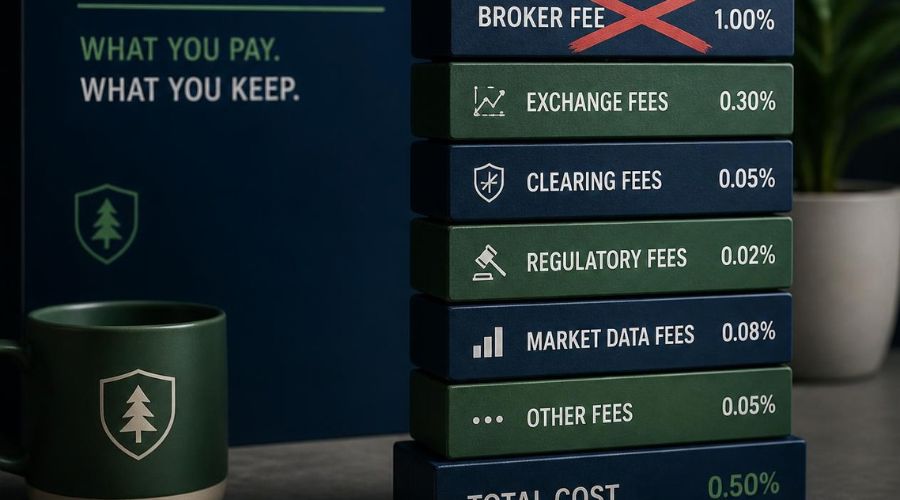
Usually it means timing - nothing payable before the application proceeds, with any fee settled at completion or paid by the lender. Money Pilot's model is simpler still: zero broker fees at every stage, funded by lender procuration, never by you.
Legitimately: assessing cases, researching lenders, packaging applications, and chasing valuations is real work, and some firms bill it at the start. Neither structure is wrong - but the fee model tells you little about advice quality.
Quality lives in lender selection, not the fee structure - the right lender for your circumstances is where the value sits. Judge brokers on market access, honesty about timelines, and completion track record; the fee question comes after.
Because transactions already stack deposits, legals, valuations, stamp duty, and refurbishment budgets - cash preserved until completion keeps the project manageable and your options open if circumstances shift.
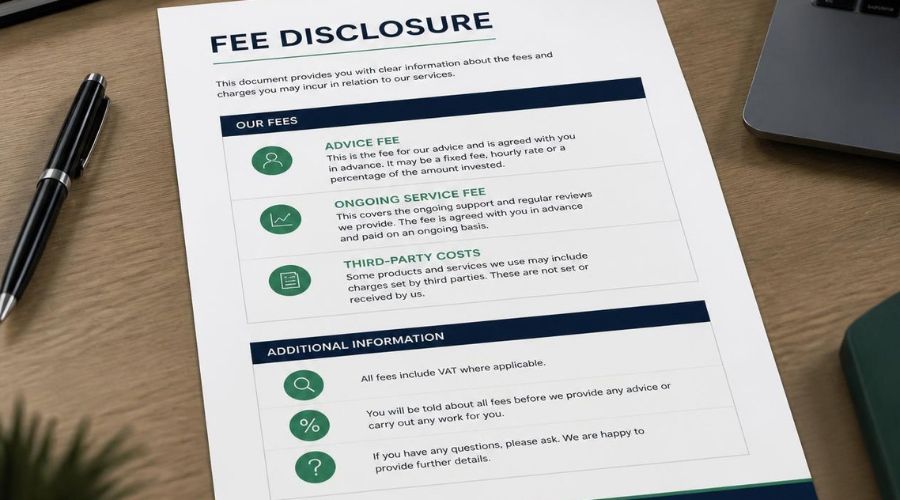
Whole-of-market access, experience in your case type, transparent fee disclosure in writing, realistic timelines, and FCA regulation. Money Pilot is directly authorised (FRN: 968705) with 200+ lenders on panel.
Nothing - zero broker fees on bridging, before, during, or after completion. You pay the lender's costs only (interest, arrangement, valuation, legals), all disclosed upfront. Call 020 4634 8617 to test it on your case.
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.