HomeArticlesCan I Use a Bridging Loan to Convert a Residential Property Into an HMO?
Can I Use a Bridging Loan to Convert a Residential Property Into an HMO?
October 2, 2026 12 Min Read
HMO & Property
✅ Can I use a bridging loan
to convert a residential property into an HMO?
Yes - it
is one of bridging’s most common uses, arguably the use case it was
tailor-made for: buying a property that isn’t mortgageable in its
current form, funding the conversion works, and refinancing onto an HMO
mortgage once the transformation - and the licensing that comes with
it - is complete. During conversion the property typically isn’t
in a state mortgage lenders will touch, and doesn’t yet hold the licence
HMO lenders want; bridging fills exactly that gap. Money Pilot has access to
200+ lenders at zero broker fees - FCA regulated (FRN: 968705).
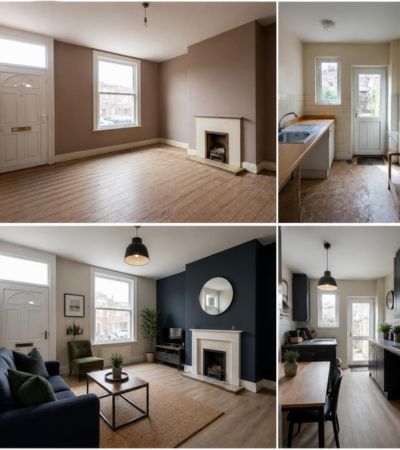
Buying a tired residential property and turning it into a
seven-bedroom HMO can be an attractive investment strategy. But there's a
problem: the property you want to buy may not qualify for a standard mortgage
once you start the conversion, and HMO lenders generally want the property
already operating as an HMO before they'll lend against it. That creates a
funding gap between purchase and refinance.
A bridging loan can fill that gap. It provides the short-term
capital to purchase the property, fund the conversion works, and carry the
project through to the point where you can refinance onto a standard HMO
mortgage. For investors using this strategy, understanding how the bridging
loan works alongside the eventual HMO refinance is essential.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
Why would you need bridging finance for an HMO
conversion?
The fundamental issue is that you're buying one type of
property and turning it into another. A standard residential property may be
perfectly mortgageable before the works begin, but once you start converting it
into an HMO, the property's use, layout, licensing requirements and value can
all change.
Many mainstream mortgage lenders don't want to finance a property
during this transition. HMO lenders, meanwhile, may require the completed
property, the correct planning position, the HMO licence, and evidence of
rental income before they'll consider a long-term mortgage.
Bridging finance sits between those two stages. You purchase
and convert using short-term finance, then refinance once the property meets
the criteria for the longer-term HMO mortgage.
What can a bridging loan actually fund?
Depending on the lender and the structure of the deal, bridging
finance can potentially cover the property purchase and some or all of the
conversion works. That might include internal alterations, additional
bathrooms, kitchens, fire safety upgrades, electrical works, heating,
decoration, and other improvements needed to bring the property up to the
standard required for an HMO.
The exact works a lender will fund, and how they release the
money, varies significantly. Some lenders may release refurbishment funds in
stages against completed works, while others structure the facility differently.
This is one reason specialist broker advice can be useful before committing to
the purchase.
How does the bridging-to-HMO process usually work?
The process typically follows a sequence like this:
- Purchase the property using bridging
finance
- Carry out the conversion works
required to create the HMO
- Obtain the relevant planning permission
and HMO licence, where required
- Complete the property and demonstrate
compliance
- Refinance onto an HMO mortgage
once the property satisfies the chosen lender's criteria
The critical point is that the exit strategy, the eventual HMO
mortgage, should be considered before the bridging facility is taken out. A
bridge isn't intended to be permanent finance; the lender needs to see how the
loan will be repaid.
What does the exit strategy mean in an HMO
conversion?
The exit strategy is simply how you intend to repay the bridging
loan. In this scenario, the intended exit is usually refinancing onto a
long-term HMO mortgage once the conversion is complete.
This means the proposed HMO mortgage needs to be realistic from
the beginning. The lender will want confidence that the finished property will
meet its lending criteria, that the anticipated rental income is achievable,
and that the final valuation will support the required refinance amount.
Can bridging finance cover the entire HMO
conversion?
Potentially, but it depends on the lender, the property, the
borrower's position and the overall loan-to-value. Bridging lenders generally
look at the value of the property, the purchase price, the proposed works, the
borrower's experience and the exit strategy when deciding how much they are
prepared to lend.
Some projects will require the borrower to contribute their own
capital towards the purchase or works. Others may be structured with a higher
level of borrowing where the overall numbers and lender criteria support
it.
How long can the bridging loan last?
Bridging loans are designed for short-term use. The exact term
depends on the lender and the project, but the facility is generally structured
to give enough time to complete the works, obtain the required approvals and
licensing, and arrange the long-term refinance.
The shorter the project can realistically be completed, the less
time the bridging facility needs to remain in place. However, allowing
insufficient time can create unnecessary pressure if the conversion or licensing
process takes longer than expected.
What happens if the HMO conversion takes longer than
expected?
This is one of the key risks to plan for. Bridging finance is
short-term and generally more expensive than a standard mortgage. If the works,
planning, licensing or refinance take longer than expected, the loan may remain
outstanding for longer and additional interest and fees can arise.
That's why a realistic project timetable and a credible exit
strategy matter so much. Building in sufficient time for unexpected delays can
help avoid being forced into a refinance before the property is genuinely ready
for an HMO lender.
Do I need planning permission to convert a property into an
HMO?
It depends on the property, the intended use and the local
planning rules. Some smaller HMOs may fall within permitted development rights,
while larger HMOs can require planning permission and may fall under a
different planning classification.
The planning position should be established before the purchase
and certainly before the bridging exit is relied upon. A property that cannot
legally operate as the intended HMO may not qualify for the planned long-term
finance.
Will I need an HMO licence?
Many HMOs require licensing, and mandatory licensing generally
applies to properties occupied by five or more people forming two or more
households who share facilities, subject to the applicable rules and local
authority requirements.
Some councils also operate additional licensing schemes that can
bring smaller HMOs within licensing requirements. The exact position therefore
needs to be checked with the relevant local authority rather than assumed.
Can a first-time HMO landlord use bridging finance?
Potentially, yes. Bridging lenders have different criteria, and
some are prepared to consider first-time HMO investors. However, the
combination of property conversion, licensing, project management and the
eventual refinance means the application needs to be particularly well
structured.
A first-time HMO landlord may strengthen the application by
using experienced contractors, professional property management and advisers
who understand HMO licensing and compliance.
What are the main costs to consider?
The cost of bridging finance is only one part of the project.
You may also need to budget for valuation fees, legal fees, arrangement fees,
planning costs, licensing costs, building works, professional fees, insurance,
and potentially additional costs associated with the eventual HMO
refinance.
A complete project appraisal should account for all of these
costs before you commit to the purchase, rather than focusing only on the
purchase price and headline bridging rate.
How does the final HMO mortgage repay the bridge?
Once the property is completed and meets the required planning,
licensing and compliance standards, an HMO lender can assess the property for
long-term finance. The new mortgage is then used to repay the outstanding
bridging balance and associated costs, subject to the new lender's valuation and
affordability criteria.
The final loan amount depends on the lender's assessment of the
completed HMO, including its value and sustainable rental income. This is why
the projected refinance should be modelled before the bridging facility is
agreed.
What is the biggest mistake with a bridging-to-HMO
strategy?
The biggest mistake is treating the bridge and the eventual HMO
mortgage as two completely separate decisions. They are connected. The
bridging loan is only viable if the planned exit is realistic.
Before purchasing, you should understand the likely completed
value, expected rental income, planning requirements, licensing position, works
needed and the type of HMO lender likely to refinance the property. That gives
you a much clearer picture of whether the project works financially.
The bottom line
A bridging loan can be a practical way to fund the purchase and
conversion of a property into an HMO when standard mortgage finance isn't
available during the works. The key is to treat the bridge as part of a
complete funding strategy, with the eventual HMO mortgage identified as the
planned exit from the outset.
For a project to work, the purchase price, conversion costs,
completed value, expected rental income, planning position, licensing
requirements and refinance need to make sense together. A specialist broker can
help structure the bridging finance and identify an appropriate HMO refinance
route across the available lender market.
FAQ
Bridging loan to convert property to hmo -
your questions answered
Yes - this is a common
bridging use: purchase a property that isn't suitable for long-term HMO
finance yet, complete the conversion, obtain licensing, and refinance onto an
HMO mortgage. The critical piece is having a credible exit and realistic
completed value.
Potentially - many
bridging lenders can include refurbishment funds, often released in stages.
Exactly what is funded, how it is released, and the maximum leverage depend on
the lender and the project.
Usually refinance onto a
long-term HMO mortgage once the conversion is complete, licensing and planning
are sorted, and the property meets the HMO lender's criteria. That refinance
should be modelled before the bridge is taken.
Requirements depend on the
property and local authority, but the long-term HMO lender will need to be
satisfied that the property can legally operate as the proposed HMO. Planning,
licensing, and compliance should therefore be addressed as part of the
conversion strategy.
The bridge may remain
outstanding for longer, potentially increasing interest and other costs.
Choosing a realistic term and allowing contingency for works, planning,
licensing and refinance is important.
We assess the purchase,
works, projected completed value, rental income, planning and licensing position
together, then match the bridge and intended HMO exit across a 200+ lender
panel at zero broker fees. Call 020 4634 8617. FCA regulated (FRN:
968705).
Disclosure:
Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone
Finance Group Ltd which is authorised and regulated by the Financial Conduct
Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not
a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You
should always make sure you are able to afford any repayments as late or missed
payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.