HomeArticlesWhich UK Lenders Offer Bridging Loans for Uninhabitable Properties?
Which UK Lenders Offer Bridging Loans for Uninhabitable Properties?
August 24, 2026 9 Min Read
Latest Articles
✅ Can I get a bridging loan on an uninhabitable property?
Yes - this is core bridging territory. Properties mainstream mortgage lenders decline (no kitchen or bathroom, structural or fire damage, failed electrics) are routinely funded by specialists including Together, Shawbrook, United Trust Bank, MT Finance, LendInvest, and Octopus Real Estate - lenders interested in what the property will become. You buy on the bridge, refurbish, then exit by mortgage or sale. Money Pilot places these cases across 200+ lenders at zero broker fees - FCA regulated (FRN: 968705).
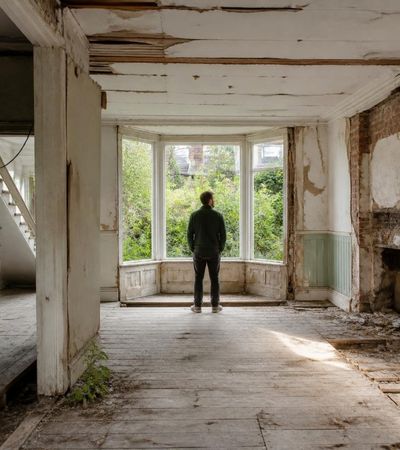
Here's something that catches a lot of buyers out. They've found exactly the property they want. The location is perfect. The price is attractive. There's just one small problem: you wouldn't want to spend a night in it.
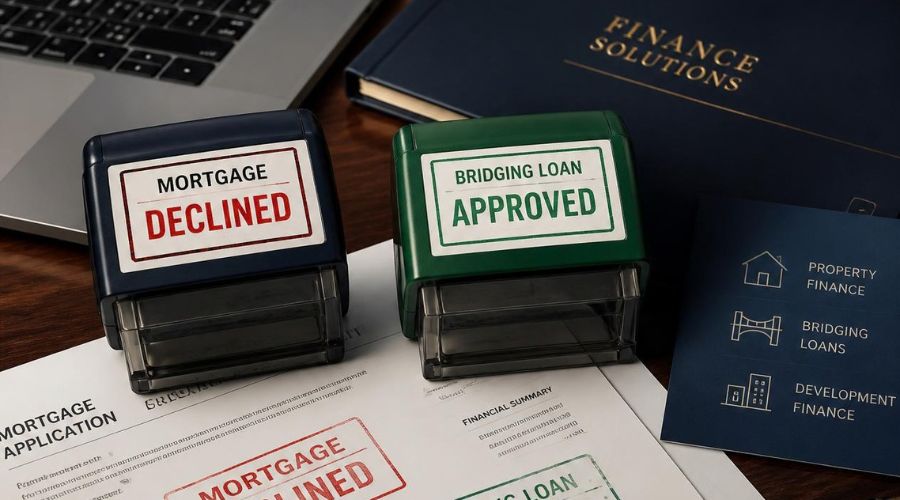
No kitchen. No bathroom. A leaking roof. Perhaps the electrics haven't been updated since England won the World Cup. They apply for a mortgage. The lender politely declines. Not because the buyer is unsuitable. Because the property is.
That's exactly where bridging finance often comes into its own.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
What counts as an uninhabitable property?
There's no universal checklist. Every lender has its own definition. But generally speaking, an uninhabitable property is one that isn't considered suitable for immediate occupation.
That could include properties with:
No functioning kitchen
No usable bathroom
Significant structural damage
Serious damp or water damage
Fire damage
Unsafe electrical systems
Missing windows or doors
Major refurbishment requirements
If someone couldn't reasonably move in tomorrow, there's a good chance many mainstream mortgage lenders will have concerns.
Why won't a normal mortgage lender finance it?
Mortgage lenders like certainty. If they're lending against a property, they want to know it has a stable value and can be occupied immediately. An empty shell with holes in the roof doesn't always fit that description.
It's not that the property has no value, it's simply outside many high street lenders' comfort zone. Bridging lenders tend to be more pragmatic. They're often interested in what the property will become, not just what it looks like today.
Which UK lenders will consider uninhabitable properties?
Quite a few specialist lenders actively lend on these types of projects, including:
Together
Shawbrook
United Trust Bank
MT Finance
LendInvest
Octopus Real Estate
Hampshire Trust Bank
InterBay Commercial
Some specialise in light refurbishment, others are comfortable with extensive renovation. A handful regularly fund properties that most mainstream lenders wouldn't consider. That's why there isn't a single best lender, there's simply the lender whose appetite matches your project.
The property matters. But so does the plan.
Imagine two identical properties. Both need complete renovation. The first buyer says, "I'm thinking of doing it up." The second says, "Here's my schedule of works, my builder's quotation, my budget and my exit strategy."
Guess which application inspires more confidence. Lenders aren't just funding buildings. They're funding plans.
What do lenders want to see?
Most specialist lenders will look at:
The property's current value
Its expected value once work is complete
The cost of the refurbishment
Your experience, where relevant
Your deposit
Your exit strategy
The proposed timescale
Notice what isn't on that list: designer kitchens, paint colours, or whether you've chosen brass or chrome taps. They're interested in whether the project makes commercial sense.
Can first-time investors get funding?
Sometimes, yes. Experience certainly helps, but it isn't always essential. A strong team, sensible costs, realistic timescales and a credible exit strategy can all strengthen an application.
Every lender has different criteria. Some actively support first-time investors, others prefer experienced developers.
What happens after the renovation?
This is where the plan comes together. Many borrowers use a bridging loan to purchase and renovate the property. Once the work is complete, they either:
Refinance onto a traditional mortgage
Move onto a buy-to-let mortgage
Sell the property
Keep it as part of a property portfolio
The bridging loan has done exactly what it was designed to do: bridge the gap.
The mistake people often make
People spend hours searching for a lender that finances uninhabitable properties. That's only half the question. The better question is this: which lender likes my type of uninhabitable property?
There's a huge difference. One lender might be perfectly happy with a property that needs a new kitchen. The next might specialise in fire-damaged buildings. Another may focus on commercial conversions. Lenders don't just have different prices, they have different personalities. Matching those personalities to the project is often where experienced brokers earn their keep.
Why using a broker can make a difference
There are dozens of specialist lenders in the UK. Each has its own criteria, its own appetite, and its own idea of what represents an acceptable level of risk. Trying to work through those criteria yourself can take days, sometimes weeks.
An experienced broker already knows which lenders are likely to say yes before the application is even submitted. That doesn't just save time. It avoids unnecessary credit searches, rejected applications and a lot of frustration.
The bottom line
Yes, there are plenty of UK lenders willing to finance uninhabitable properties. The challenge isn't finding one, it's finding the right one.
A property that's unsuitable for a traditional mortgage isn't necessarily a bad investment. Quite often, it's simply a specialist one. And specialist opportunities are exactly what bridging finance was built for.
FAQ
Bridging loan uninhabitable property uk - your questions answered
No universal checklist - each lender defines it - but the common markers are no functioning kitchen or usable bathroom, structural, fire, or serious damp damage, unsafe electrics, or missing windows and doors. If nobody could reasonably move in tomorrow, expect mainstream concern.
Mortgage lending wants immediate occupability and stable value; an empty shell sits outside that comfort zone. It is a property problem, not a borrower problem - which is why the same buyer sails through with a bridging specialist.
An active specialist market: Together, Shawbrook, United Trust Bank, MT Finance, LendInvest, and Octopus Real Estate among the established names - each with its own appetite by damage type, location, and borrower experience. Matching case to lender is the craft.
Bridge to buy (often at auction), fund or self-fund the refurbishment, then exit: refinance onto a residential or buy to let mortgage once the property qualifies, or sell it improved. The exit evidence is what underwrites the whole journey.
Pricing follows condition and plan - heavier works and lower day-one values can mean slightly higher rates or LTVs set against the current value with works funded in stages. A credible schedule of works and contingency moves pricing your way.
By matching the damage profile, works plan, and exit to the lenders who genuinely like that shape - terms compared across 200+ lenders, zero broker fees, FCA regulated (FRN: 968705). Call 020 4634 8617 before you bid, not after.
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.