Commercial mortgage deposit UK - how much in 2026?
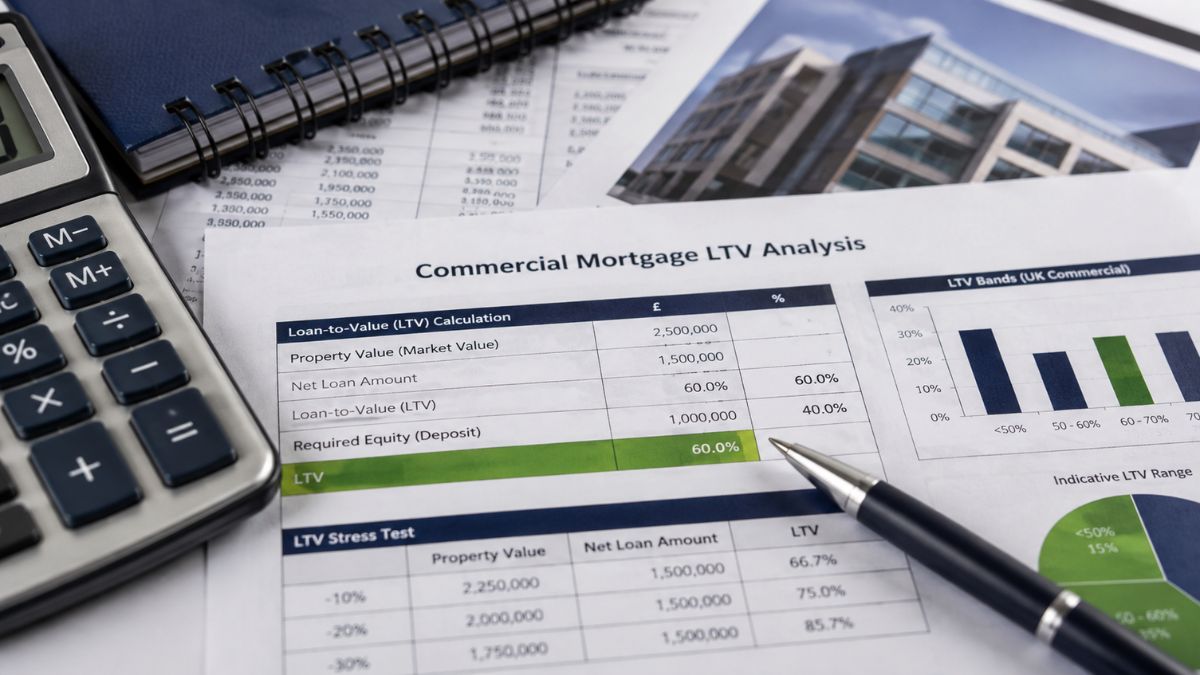
Commercial mortgage deposits are expressed through loan to value (LTV) - the percentage of the property value the lender will advance. The deposit is the rest. Commercial mortgage LTV UK lenders offer in 2026 by asset type:
- Owner-occupied trading premises: 70–80% LTV → deposit 20–30%
- Commercial investment property: 65–75% LTV → deposit 25–35%
- Semi-commercial / mixed use: 70–75% LTV → deposit 25–30%
- Specialist assets (hotels, care, leisure): 60–70% LTV → deposit 30–40%
On a £500,000 owner-occupied purchase at 75% LTV, the deposit is £125,000 - plus stamp duty, legal, and valuation costs on top. Compare the full commercial mortgages market before assuming your deposit figure: the same case can be quoted 10% LTV apart by different lenders.
Why commercial deposits are higher than residential
Commercial property values move with business conditions, tenant covenants, and lease events, so lenders hold a larger equity cushion. Owner-occupied cases carry business trading risk; investment cases carry void and re-letting risk. The deposit is the lender’s protection against both - which is also why stronger cases genuinely achieve lower deposits.
What moves your LTV up - and your deposit down
- Trading strength - 2–3 years of profitable accounts with clear debt service cover
- Tenant covenant - for investments, a strong tenant on a long lease with no breaks
- Asset quality - standard, re-lettable buildings in established locations
- Sector - matching your sector to the right lender’s appetite adds 5–10% LTV
- Experience - landlords with managed portfolios borrow higher than first-timers
Five legitimate ways to reduce your cash deposit
1. Additional security
Offering a charge over another property - commercial, or residential with sufficient equity - can take borrowing to 100% of the purchase price while the lender’s exposure stays within its LTV rules across the combined security. This is the most common route for strong businesses that are asset-rich but cash-light. See also secured business loans.
2. The Growth Guarantee Scheme
For qualifying owner-occupied purchases, the government-backed Growth Guarantee Scheme gives the lender a 70% guarantee - which several lenders convert into higher LTVs or acceptance of cases otherwise declined.
3. Vendor deferred consideration
The seller leaves part of the price outstanding as a subordinated loan repaid over time - effectively part-funding your deposit. This is common in business-with-premises sales where the vendor wants the deal to complete.
4. Directors’ loans and gifted deposits
Funds introduced by directors or family are acceptable to most lenders with clean documentation of source and, where required, subordination to the lender’s facility.
5. Buying below market value
Some lenders will lend against valuation rather than price on genuine below-market purchases - probate, receivership, inter-company transfers - reducing the cash required to complete.
Commercial mortgage requirements UK beyond the deposit
Commercial mortgage requirements UK lenders apply go well beyond the deposit percentage. Knowing the full checklist before applying is what turns a marginal case into an approved one.
What lenders assess alongside your deposit:
- Debt service cover - rental or trading profit comfortably above the mortgage payment at a stressed rate
- Accounts, bank statements, and management information for owner-occupiers
- Lease terms, tenant strength, and WAULT for investment purchases
- Personal guarantees - standard on most limited-company borrowing
- Clean legal title with an acceptable environmental and planning position
Commercial mortgage requirements UK - debt service cover, accounts, lease quality, and guarantees are weighed alongside the deposit. Money Pilot prepares your case for the right lender first time.
Deposit examples by purchase price
To make the numbers concrete, here is what the commercial mortgage deposit UK buyers should budget looks like at three common purchase levels, assuming a standard owner-occupied case at 75% LTV:
- £300,000 purchase: deposit £75,000 - plus roughly £9,500 for SDLT, legals, valuation, and fees
- £500,000 purchase: deposit £125,000 - plus roughly £17,500 in transaction costs
- £1,000,000 purchase: deposit £250,000 - plus roughly £42,000 in transaction costs
Investment purchases at 70% LTV add 5% to each deposit figure; specialist assets at 65% add 10%. These are planning figures - the lender’s valuation, not the price, ultimately sets the advance, which is why below-market purchases can work in your favour.
Commercial property deposit rules UK - the practical points
Commercial property deposit rules UK lenders apply also cover the source of your deposit - expect anti-money-laundering checks on where funds originate - and the timing, with deposits payable at exchange (typically 10%) and completion. Budget separately for stamp duty land tax, both sides’ legal fees, valuation, and the arrangement fee (typically 1- 2%, usually addable to the loan).
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.