HomeArticlesWhat Is the Difference Between a Commercial Mortgage and a Buy-to-Let Mortgage?
What Is the Difference Between a Commercial Mortgage and a Buy-to-Let Mortgage?
September 15, 2026 9 Min Read
Product Comparison
✅ Commercial vs residential
mortgage - what's actually different?
Commercial
mortgages are assessed around the property, business income and debt service
rather than just personal salary. Expect lower LTV (typically 65–75%),
DSCR testing, shorter terms in some cases, and more bespoke underwriting. The
trade-off is flexibility: commercial finance can fund offices, shops,
industrial units and mixed-use property, whether you occupy it or let it. Money
Pilot compares 200+ lenders at zero broker fees, FCA regulated (FRN:
968705).
If you've only ever dealt with residential mortgages, stepping
into commercial property finance can feel like the rules have changed
completely. In some ways, they have. The principles are similar, but lenders
look at the deal through a very different lens.
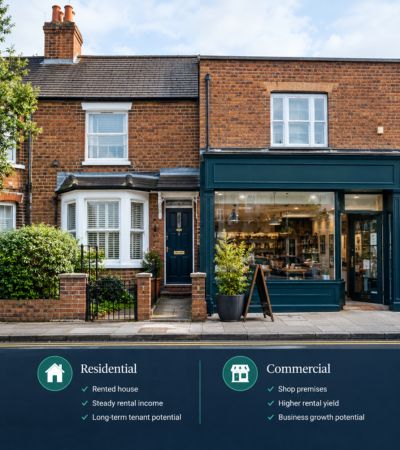
The biggest difference is that a residential mortgage is largely
about you - your salary, your personal outgoings, your credit history.
A commercial mortgage is much more about the property and the income it
generates, whether that's rental income or trading income from the business
occupying the premises.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
What is the main difference between commercial and residential
mortgages?
The fundamental difference is what the lender is assessing. With
a residential mortgage, the lender is primarily asking whether your personal
income can comfortably support the monthly repayment.
With a commercial mortgage, the lender is looking at the property
and the business or rental income behind it. They want to know whether the
asset can support the debt and whether there is enough margin if circumstances
change.
How does the loan-to-value differ?
Residential mortgages can sometimes reach 90% or 95% LTV,
depending on the borrower and circumstances. Commercial mortgages are generally
lower, with 65-75% LTV being a realistic planning range for many
straightforward cases.
That means you should generally expect to contribute a larger
deposit when buying commercial property. Some particularly strong commercial
cases can reach higher LTVs, while specialist or higher-risk property may be
limited to substantially less.
Why is commercial mortgage underwriting more
complicated?
Because there are more variables to consider. The lender may
look at:
- The property's current and expected income
- The property's type and location
- The strength of any tenant covenant
- The borrower's business and trading history
- The borrower's experience and financial position
- The DSCR and lender stress testing
- The property's valuation and marketability
A residential mortgage generally has a much more standardised
assessment process.
What is DSCR and why does it matter for commercial
mortgages?
DSCR stands for Debt Service Coverage Ratio. It measures whether
the income generated by the property or business is sufficient to cover the
mortgage repayments.
For example, if annual net operating income is £30,000 and annual
mortgage repayments are £24,000, the DSCR is 1.25x.
Commercial lenders often have minimum DSCR requirements and may
also stress-test the calculation against a higher interest rate.
Are commercial mortgage interest rates higher than residential
rates?
Commercial mortgage rates are often higher than standard
residential mortgage rates because the underlying risk and underwriting are
different. Pricing depends on the property, LTV, borrower, income, loan size,
term, and lender appetite.
There is no single commercial mortgage rate that applies to every
borrower. Comparing lenders based on the complete structure of the deal is
usually more useful than comparing headline rates alone.
Are commercial mortgage terms different?
They can be. Residential mortgages are commonly available over
longer terms, while commercial mortgages may have shorter repayment periods
depending on the lender and structure.
Commercial loans may also be structured with interest-only
periods, repayment mortgages, or other arrangements depending on the lender's
criteria and the purpose of the borrowing.
Can you use a commercial mortgage for a property you occupy
yourself?
Yes. If a business is buying premises to operate from, such as
an office, shop, warehouse or industrial unit, an owner-occupied commercial
mortgage may be appropriate.
The lender will typically assess the business's trading
performance and ability to service the mortgage, rather than relying solely on
the borrower's personal income.
Can you use a residential mortgage to buy commercial
property?
Generally, no. If the property is genuinely commercial in use,
you will usually need commercial property finance rather than a standard
residential mortgage.
Mixed-use property can be more complicated. The appropriate
finance depends on the residential and commercial proportions, how the property
is used, and the lender's criteria.
What types of property can commercial mortgages
finance?
Depending on the lender, commercial mortgages can be used for
properties such as:
Offices
Retail
units and shops
Industrial
and warehouse units
Mixed-use
properties
Investment
properties
Specialist
commercial property, subject to lender appetite
Which mortgage is right for you?
There isn't a universal answer. The right structure depends on
what you are buying, whether you will occupy or let the property, how much you
need to borrow, the available deposit, the income supporting the loan, and your
long-term plans.
The key is matching the case to a lender whose criteria fit the
deal rather than trying to force every application through the same type of
mortgage.
The bottom line
Commercial and residential mortgages share the same basic idea -
borrowing money against property - but the way lenders assess the risk is
very different.
Commercial finance generally involves lower LTVs, DSCR
calculations, more detailed underwriting, and more bespoke lending criteria.
Understanding those differences before you apply can help you approach the
right lenders with realistic expectations.
FAQ
Commercial mortgage vs residential mortgage -
your questions answered
Residential lending focuses
primarily on personal income and affordability. Commercial lending assesses
the property, business or rental income, DSCR, LTV, borrower profile and the
specific risks of the deal.
The process can be more involved
because there are more variables for the lender to assess. However, the right
commercial lender may be able to accommodate a case that does not fit standard
residential criteria.
They are often higher, although
the actual rate depends on the lender, LTV, property, borrower, loan amount,
term and overall risk profile.
Commercial LTV limits are
generally lower than residential mortgages, so a larger deposit is commonly
required. The exact amount depends on the property and lender.
Yes. Owner-occupied commercial
mortgages can be used by businesses purchasing premises such as offices,
shops, warehouses and industrial units, subject to lender criteria.
Money Pilot compares suitable
commercial lenders based on the property, borrower and loan requirements across
200+ lenders. There are zero broker fees. Call 020 4634 8617. FCA regulated
(FRN: 968705).
Disclosure:
Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone
Finance Group Ltd which is authorised and regulated by the Financial Conduct
Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not
a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You
should always make sure you are able to afford any repayments as late or missed
payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.