HomeArticlesWhat Is Consumer Duty and How Does It Protect Commercial Finance Borrowers?
What Is Consumer Duty and How Does It Protect Commercial Finance Borrowers?
September 01, 2026 9 Min Read
Business Finance
✅ Does Consumer Duty
protect commercial finance borrowers?
Sometimes
- and the nuance matters. Consumer Duty (in force since July 2023)
requires regulated firms to deliver good outcomes across products, price and
fair value, understanding, and support - for retail-scope business,
which can include sole traders, micro-enterprises, and smaller SMEs on
FCA-regulated activities. It generally does not cover unregulated commercial or
wholesale lending. Money Pilot applies regulated conduct standards across its
brokerage - FCA regulated (FRN: 968705).
Introduced by the Financial Conduct Authority, Consumer Duty
came into force at the end of July 2023, and it represents one of the more
significant shifts in UK financial regulation in recent years. But its
protection for commercial finance borrowers specifically isn't quite as simple
as "it covers everyone", it depends on the type of finance and the
nature of the borrower, and understanding that nuance matters if you want to
know exactly what protection you're actually entitled to.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
What is Consumer Duty?
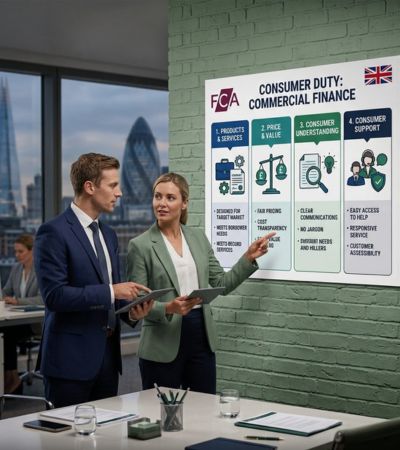
Consumer Duty is an FCA regulatory standard requiring regulated
firms to deliver good outcomes for retail customers across four key areas: the
products and services themselves, price and fair value, consumer understanding,
and consumer support. Rather than simply avoiding harm, firms are required to
actively demonstrate they're delivering genuinely good outcomes, not just
meeting a minimum bar of acceptable conduct.
Does Consumer Duty apply to all commercial finance
borrowers?
Not automatically, and this is worth understanding clearly
rather than assuming blanket coverage. Consumer Duty applies to a firm's retail
market business, and "retail customer" is a broader category than the
general public, it can include SMEs, micro-enterprises, and, depending on the
specific regulated activity involved, sole traders and smaller business
borrowers too. However, the Duty generally does not apply to unregulated
commercial or wholesale lending, and it specifically does not extend to large
business mortgage customers or SME lending that falls outside FCA-regulated
credit activities.
In practice, this means whether Consumer Duty protection applies
to a specific commercial finance borrower depends on the exact type of finance
being arranged, and whether that particular activity falls within FCA-regulated
scope, rather than being a blanket guarantee across every kind of business
lending.
Where does Consumer Duty most clearly apply in commercial
finance?
Generally, where the finance activity itself is FCA-regulated
and the borrower meets the relevant "retail customer" definition for
that specific type of product, commonly including sole traders,
micro-enterprises, and certain smaller business borrowers depending on the
regulated activity involved, regulated mortgage contracts being one clear
example.
Where does it typically not apply?
Consumer Duty generally doesn't extend to unregulated commercial
or wholesale lending, or to larger business borrowers whose finance falls
outside FCA-regulated credit activities altogether. A large, established
company arranging a substantial unregulated commercial loan sits in a genuinely
different position to a sole trader or micro-enterprise taking out finance that
falls within FCA-regulated scope.
What are the four outcomes Consumer Duty actually requires,
where it applies?
Products and services. Designed to
meet the genuine needs of the target customer group, not simply designed for
profitability with the customer as an afterthought.
Price and value. Customers should
receive fair value for what they're paying, not simply whatever the market will
bear regardless of what's actually being delivered.
Consumer understanding.
Communications need to be clear, and genuinely understandable to the customer,
not technically accurate but practically confusing.
Consumer support. Customers should
be able to get the help they need, when they need it, throughout the life of
the product or service, not just at the point of sale.
Why does this matter for how a broker operates, even beyond
strict legal scope?
Because many firms, including those operating in commercial
finance more broadly, choose to apply Consumer Duty principles as good practice
across their business, even in areas that fall technically outside the Duty's
strict regulatory scope. A broker genuinely committed to treating customers
fairly tends to apply similar standards, clear communication, fair value,
genuine support, consistently, rather than drawing a hard line exactly where
legal obligation stops.
How does this connect to being "FCA regulated" more
broadly?
FCA regulation and Consumer Duty aren't quite the same thing, a
firm can be FCA regulated while some of its specific activities sit outside
Consumer Duty's precise scope. That said, firms genuinely committed to treating
customers fairly as a principle, not just a legal minimum, tend to reflect
Consumer Duty's underlying spirit, clear communication, fair value, genuine
support, across their business generally, rather than only where strictly
legally required.
What should you check as a commercial finance
borrower?
A few things worth confirming with any broker or
lender:
- Whether the specific type of finance you're arranging falls
within FCA-regulated activity
- Whether you, as a borrower, would meet the "retail
customer" definition relevant to that specific product
- Whether the firm applies fair treatment principles
consistently, regardless of the precise legal boundary
The mistake people often make
Some assume Consumer Duty provides blanket protection across
every type of commercial finance, only to discover later that a specific large
or unregulated commercial lending arrangement sits outside its strict scope.
Understanding the actual boundary, regulated activity and retail customer
status, rather than assuming universal coverage, gives a genuinely accurate
picture of where legal protection applies.
The bottom line
Consumer Duty requires FCA regulated firms to deliver good
outcomes across products, price, understanding, and support, but its
application to commercial finance borrowers depends on whether the specific
activity is FCA-regulated and whether the borrower meets the relevant retail
customer definition, it doesn't blanket-cover every type of business lending.
Money Pilot's regulatory content covers this in more depth, reflecting its position
as an FCA regulated broker committed to treating customers fairly, both within
Consumer Duty's strict legal scope and as a broader operating principle across
its business.
FAQ
Consumer duty commercial finance - your
questions answered
Products and services fit
for purpose; price and fair value; consumer understanding (communications that
genuinely inform); and consumer support throughout the relationship. Firms must
actively demonstrate good outcomes, not merely avoid
harm.
Possibly - the category
is broader than the general public: sole traders, micro-enterprises, and
certain smaller business borrowers can fall within it, depending on the
specific regulated activity. It is an activity-by-activity test, not a blanket
status.
Unregulated commercial
and wholesale lending generally, including larger business mortgages and SME
lending outside FCA-regulated credit activities. Outside the Duty's scope, the
broker's own regulated conduct standards still apply - which is why the
broker's status matters.
The bar moves from 'avoid
causing harm' to 'demonstrate good outcomes' - fair value assessments,
communications tested for real understanding, and support that works when you
need it, evidenced to the regulator on an ongoing
basis.
Ask directly: is this
activity FCA-regulated, and do I meet the retail customer definition for it? A
straight answer to both is itself a good sign - regulated brokers can tell you
precisely where your case sits.
As a regulated broker
(FRN: 968705) we operate within the Duty where it applies and hold the same
conduct standards - clear disclosure, fair treatment, honest communication -
across all our commercial finance work. Call 020 4634
8617.
Disclosure:
Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone
Finance Group Ltd which is authorised and regulated by the Financial Conduct
Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not
a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You
should always make sure you are able to afford any repayments as late or missed
payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.