HomeArticlesWhat Is a First Charge and Second Charge Bridging Loan?
What Is a First Charge and Second Charge Bridging Loan?
August 19, 2026 9 Min Read
Product Comparison
✅ What is the difference between a first and second charge bridging loan?
Repayment priority: a first charge lender stands first in the queue if the property is sold; a second charge lender sits behind an existing lender (usually your mortgage) and is repaid from what remains. Second charge bridges let you raise funds while keeping a competitively priced mortgage in place - often with the existing lender’s consent and sufficient equity required. Money Pilot arranges both across 200+ lenders at zero broker fees - FCA regulated (FRN: 968705).
For something lenders talk about every day, "first charge" and "second charge" sound far more complicated than they really are. In truth, they have nothing to do with the type of property, the size of the loan, or even the interest rate. They're simply about one thing: who gets paid first if the property has to be sold?
Once you understand that, the rest becomes surprisingly straightforward.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
What is a first charge bridging loan?
A first charge bridging loan is secured against a property that either has no mortgage, or where the bridging lender becomes the first lender with legal priority over the property. If the property were ever sold to repay debts, the first charge lender would be paid before anyone else.
Think of it as standing first in the queue. If there's enough money to pay everyone, wonderful. If there isn't, the person at the front of the queue gets paid first. That's why first charge lending is generally considered lower risk.
What is a second charge bridging loan?
A second charge bridging loan works slightly differently. Here, there's already another lender with a first charge over the property, usually a mortgage lender. The bridging lender agrees to sit behind them.
If the property ever had to be sold, the mortgage lender would be repaid first. The bridging lender would receive what's left afterwards. That's why second charge lending is usually viewed as carrying a little more risk.
A simple example
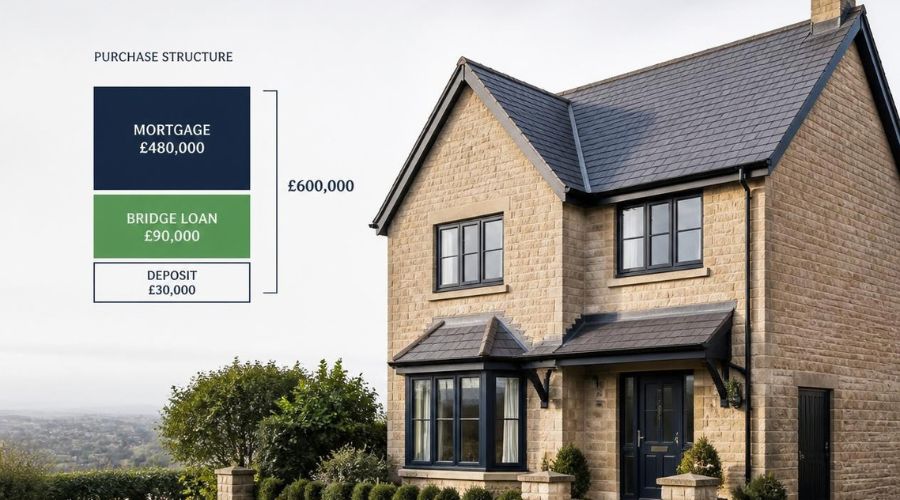
Imagine your property is worth £600,000. You already have a mortgage of £250,000. You now want to borrow another £100,000 using a bridging loan.
Your mortgage lender keeps the first charge. The bridging lender takes a second charge. If the property were sold, the mortgage would be repaid first, and the bridging lender would then receive repayment from the remaining proceeds. It's simply about the order in which lenders are paid. Nothing more mysterious than that.
Why would someone choose a second charge bridge?
A fair question. After all, wouldn't it be easier to replace the existing mortgage? Not always. Perhaps your current mortgage has an excellent interest rate that you'd rather keep. Perhaps there are early repayment charges. Perhaps refinancing the whole property simply doesn't make financial sense.
A second charge bridge allows you to raise additional funds without disturbing the mortgage that's already in place. For many borrowers, that's an attractive option.
Is one better than the other?
Not really. They're designed for different situations. A first charge bridge makes sense when:
You're buying a new property
The property has no mortgage
Existing borrowing is being repaid
The bridging lender will become the primary lender
A second charge bridge may be more suitable when:
You want to keep your existing mortgage
You need to release equity
Your current mortgage is competitively priced
Replacing your existing finance would be unnecessarily expensive
The right answer depends entirely on your circumstances.
Are second charge bridging loans more expensive?
Often, yes. Remember the queue: the lender standing second takes more risk than the lender standing first, and that additional risk is often reflected in the pricing.
But "more expensive" doesn't automatically mean "poor value." If a second charge loan allows you to keep an excellent mortgage rate while raising the funds you need, it may still be the more cost-effective option overall.
Do both require an exit strategy?
Without question. Whether the loan is first charge or second charge, the lender still wants to understand how the borrowing will be repaid. That could be:
Selling the property
Refinancing
Completing a development
Selling another asset
Releasing funds from another source
The charge position changes the lender's security. It doesn't remove the need for a clear repayment plan.
Can every property have a second charge loan?
Not necessarily. The existing mortgage lender may need to consent. There also needs to be enough equity in the property for the additional borrowing to make sense. Every lender has its own criteria, which is why second charge cases often require a little more planning than straightforward first charge loans.
The biggest misconception
Many people hear "second charge" and assume it means second best. It doesn't. It simply describes legal priority.
Some of the most experienced property investors in the country regularly use second charge lending because it allows them to unlock equity while keeping favourable long-term borrowing in place. It's a financial tool. Like any tool, its value depends on how and when it's used.
The bottom line
The difference between a first charge and a second charge bridging loan is surprisingly simple. A first charge lender stands first in line for repayment. A second charge lender stands behind an existing lender. Neither is inherently better. Neither is inherently worse. They're simply designed to solve different funding challenges.
The key isn't choosing between first and second charge. It's understanding which structure gives you the greatest flexibility while supporting your overall property strategy
FAQ
First charge vs second charge bridging loan - your questions answered
Buying a new property, borrowing against an unmortgaged one, or where existing borrowing is being repaid so the bridging lender becomes the primary lender. It is the lower-risk position and generally the wider, keener-priced market.
To leave a good mortgage untouched - an excellent rate, or early repayment charges that make refinancing the whole property poor value. The second charge raises the extra funds on top without disturbing what already works.
Often somewhat - the lender behind in the queue carries more risk and prices it. But keeping a cheap first mortgage frequently makes the second charge the cheaper overall structure; judge the total cost, not the single rate.
Usually yes - the existing first charge lender's consent is typically required, and there must be enough equity to support the additional borrowing. Both are checked early; neither is normally a deal-breaker on sensible cases.
Absolutely - the charge position changes the lender's security, not the need for a credible repayment plan. Sale, refinance, development completion, or another evidenced source: the exit rules apply identically.
On your numbers - existing rate, ERCs, equity, and the purpose of funds - modelling both routes across 200+ lenders and running the consent process where second charge wins. Zero broker fees. Call 020 4634 8617. FCA regulated (FRN: 968705).
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.