Mixed use property investment UK - why the economics work
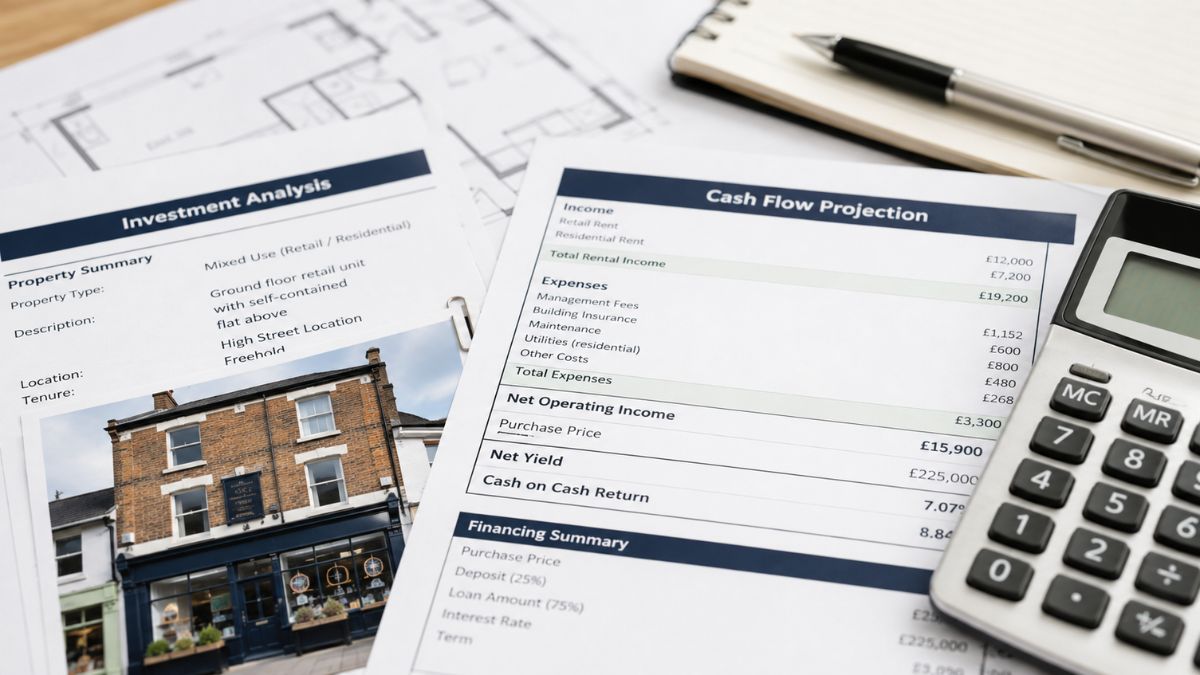
The model’s strength is complementary income. The commercial unit lets on a full repairing and insuring (FRI) lease - the tenant maintains their unit and often contributes to the building - producing hands-off income at commercial yields. The flats above let on standard ASTs at residential demand levels. One freehold, one insurance policy, one roof - two markets paying rent, rarely soft in the same season. When retail wobbles, the flats carry the building; when residential voids bite, the shop’s lease runs on.
Semi commercial property yields UK investors achieve in 2026 typically run 7-10% gross - against 5-6% for comparable pure residential - with the strongest results where the commercial tenant is essential-local (convenience, pharmacy, takeaway, barber) rather than fashion-exposed retail.
The tax advantage buyers miss
- Non-residential SDLT rates apply to genuine mixed use purchases - lower bands than residential at most price points
- No 3% additional-property surcharge - the saving that transforms the comparison: on a £500,000 purchase, a mixed use classification typically saves £15,000-£25,000 against a residential BTL of the same price
- Classification is substance-based - the commercial element must be real and in use; HMRC challenges token classifications, so document the trading reality
- Ownership structure still matters - company versus personal follows the same logic as any rental investment; take advice on your position
Flat above shop investment UK - the classic entry point
Flat above shop investment UK deals are where most investors enter the sector, and the checklist is specific:
- Separate access - flats with their own entrance let better, value higher, and satisfy more lenders than access-through-the-shop layouts
- The commercial covenant - years trading, lease length remaining, and rent honestly benchmarked against the parade
- The lease terms - FRI or internal-only, break clauses, rent review pattern, and any user restrictions
- Use compatibility - the takeaway below affects the flat’s letting appeal; the pharmacy does not
- Condition split - who owns which repairs: the roof above the flat, the shopfront below it, the party structures between
Mixed use mortgage lenders UK - how the market prices it
Mixed use mortgage lenders UK operate a specialist market - mainstream residential lenders decline the shop, mainstream commercial lenders under-love the flats. The specialists price the whole.
What the 2026 semi-commercial market looks like:
- LTVs of 70-75% on the combined value - the strongest terms where residential exceeds half the floor area
- Pricing between BTL and full commercial - typically 1-2% above pure residential BTL
- Serviceability tested on both incomes - the commercial rent and the AST income each assessed on their own rules
- Valuations reflect both markets - investment value on the shop, comparables on the flats
- Lender appetite varies by split - 30% commercial funds very differently from 70%: match the lender to the building
Mixed use mortgage lenders UK price the whole building - LTVs to 75%, both incomes tested, appetite set by the commercial split.
Managing the two halves - the operational reality
Mixed use rewards investors who respect that they are running two tenancies under two legal regimes. The commercial lease runs on contract law - rent reviews, dilapidations, and renewal rights under the Landlord and Tenant Act; the flats run on AST regulation - deposits, licensing where applicable, and possession rules. The workload is lighter than it sounds - the FRI lease outsources most commercial maintenance - but the knowledge requirement is real, and the investors who thrive either learn both regimes or appoint agents who hold them.
Building the portfolio - where mixed use leads
For scaling investors, mixed use is often the yield engine inside a wider book - the 8-9% gross assets that lift a portfolio’s blended cover for the aggregate tests covered in our portfolio landlord rules UK guide. Financing scales the same way: single assets on mixed use property finance, larger holdings onto blended portfolio facilities, with commercial mortgage structures available where the commercial element dominates. The sector’s pricing inefficiency is the opportunity - and it favours the prepared.
Value-add angles the sector rewards
Mixed use carries development optionality most buyers ignore: upper parts split into additional flats, permitted development conversions above the retained shop, and lease regears that re-rate the commercial value overnight. Buying the tired parade freehold at its current-income price and releasing those angles is the sector’s classic value play - funded at purchase on the standing income, refinanced after works at the improved one.
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.