HomeArticlesWhat Is the Difference Between Retained and Rolled Up Bridging Interest?
What Is the Difference Between Retained and Rolled Up Bridging Interest?
August 21, 2026 9 Min Read
Product Comparison
✅ What is the difference between retained and rolled up bridging interest?
When the interest is accounted for. Retained: the lender calculates the term’s interest at the start and sets it aside from the loan - nothing monthly, already handled. Rolled up: interest accumulates on the balance through the loan and is paid when you exit. Both avoid monthly repayments; neither is automatically cheaper - the transaction decides. Money Pilot models both across 200+ lenders at zero broker fees - FCA regulated (FRN: 968705).
If you've started looking into bridging finance, you've probably come across two phrases that sound as though they belong in a bakery: retained interest and rolled up interest. The good news is they're much simpler than they sound. The difference comes down to one question: when does the interest get accounted for? Not whether you pay it. Not how much you pay. Just when it's dealt with.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
First things first
Unlike a traditional mortgage, many bridging loans don't require you to make monthly repayments. That's one of the reasons they're so popular. If you're renovating a property or waiting for another property to sell, the last thing you usually want is another monthly bill landing on the doormat.
Instead, many lenders allow the interest to be dealt with when the loan ends. That's where retained and rolled up interest come in.
What is retained interest?
Retained interest is calculated at the beginning of the loan. The lender works out how much interest will be payable over the agreed loan term, and that amount is then set aside from the loan itself.
Imagine you're borrowing £300,000 over twelve months. The lender calculates the expected interest for those twelve months. Rather than asking you to make monthly payments, they simply retain that amount when the loan completes. You don't make monthly repayments because the interest has already been accounted for. It's one less thing to think about while you're focusing on the property.
What is rolled up interest?
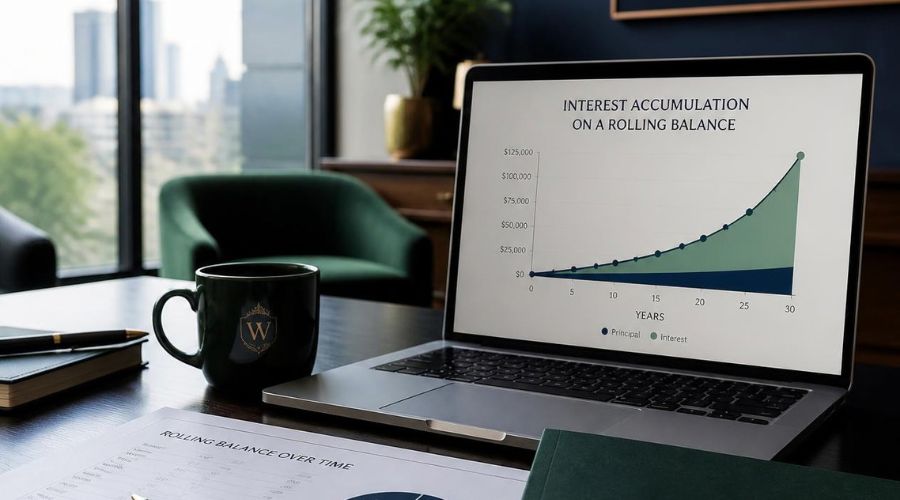
Rolled up interest works slightly differently. Instead of being calculated and set aside at the beginning, the interest builds up throughout the life of the loan. Nothing is paid each month, the interest simply accumulates.
When the loan is repaid, the outstanding interest is paid at the same time. Think of it as adding each month's interest to the running total until the loan reaches its natural conclusion.
So what's the practical difference?
Imagine two borrowers. Both take out identical bridging loans. The first chooses retained interest, and the lender deducts the expected interest from the loan on day one. The second chooses rolled up interest, and receives the full loan amount, with the interest added to the balance over time.
Both borrowers avoid monthly repayments. The difference lies in how the interest is managed during the loan.
Which option is better?
Neither. They're designed for different circumstances. Retained interest can work well if you know exactly how long you'll need the loan. Rolled up interest may offer greater flexibility if the timing of your exit is less predictable. The right answer depends on the transaction rather than the terminology.
Does one cost more?
Not automatically. People often assume rolled up interest must be more expensive, or that retained interest is somehow cheaper. It isn't that simple. The total cost depends on factors such as:
The interest rate
The loan amount
How long you keep the loan
The lender's pricing
The terms of the agreement
The method of charging interest is only one part of the calculation.
Why do borrowers choose these options?
Cash flow. It's as simple as that. Imagine you're buying a property that needs six months of refurbishment. You're paying builders, buying materials, covering legal fees, perhaps paying architects. Making monthly loan repayments on top of everything else isn't always the best use of your cash.
Retained and rolled up interest allow borrowers to concentrate on the project rather than worrying about monthly payments.
Can you repay the loan early?
Often, yes. Many bridging loans can be repaid before the agreed end date. Whether that reduces the amount of interest payable depends on the lender and the product you've chosen. Some lenders charge interest only for the time you've actually borrowed the money. Others have minimum interest periods or different charging structures. It's one of those details that's well worth understanding before you sign anything.
The mistake people often make
Borrowers sometimes become fixated on whether interest is retained or rolled up. Experienced investors usually focus somewhere else. They ask whether the overall loan suits the transaction, because a slightly different interest structure rarely makes or breaks a good deal. Choosing the wrong lender often does.
The bottom line
Retained and rolled up interest both allow borrowers to avoid making monthly repayments during the life of a bridging loan. Retained interest is calculated and set aside at the beginning of the loan. Rolled up interest builds throughout the loan and is repaid when the borrowing comes to an end.
Neither option is inherently better. They're simply different ways of structuring the same objective. The important question isn't which one sounds better, it's which one fits your project, your cash flow and your exit strategy most effectively.
FAQ
Retained vs rolled up interest bridging - your questions answered
No - that is one of bridging's defining features. Serviced (monthly) interest exists for borrowers with income who prefer it, but retained and rolled-up structures let renovators and sellers run the project without a monthly bill.
The lender calculates expected interest for the agreed term and deducts it from the advance on day one - borrowing £300,000 over twelve months means the twelve months' interest is set aside at completion, and nothing falls due monthly.
You receive the fuller advance and interest accrues onto the balance month by month, all settled when the loan repays. Same no-monthly-payments outcome, different mechanics - and different cash-at-day-one arithmetic.
Neither automatically - total cost depends on rate, term used, and how each lender computes the structure. Retained can suit known timelines; rolled-up can suit uncertain exits. Model both on your actual numbers before choosing.
Many lenders offer hybrids - part serviced, part rolled - or early-exit recalculations where unused retained interest is credited. Structure flexibility varies by lender, which is exactly where whole-market comparison earns its keep.
We run your exit timeline against both structures across 200+ lenders - day-one cash, total cost, and flexibility compared side by side - at zero broker fees. Call 020 4634 8617. FCA regulated (FRN: 968705).
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.