HomeArticlesWhat Are SWAP Rates and How Do They Affect UK Commercial Mortgages?
What Are SWAP Rates and How Do They Affect UK Commercial Mortgages?
September 10, 2026 9 Min Read
Rates & Costs
✅ What are SWAP rates and
how do they affect commercial mortgages?
A SWAP rate
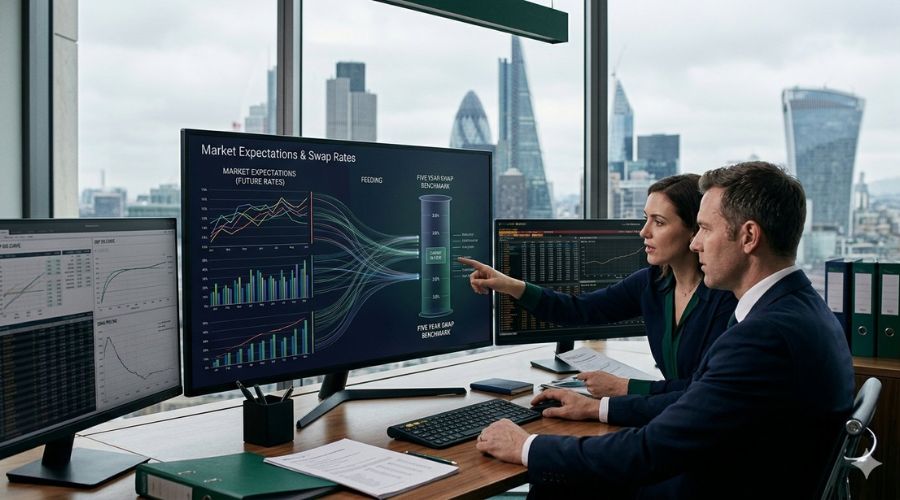
reflects what financial markets expect average interest rates to be over a
future period - commonly two, three, or five years - and
lenders price fixed-rate commercial mortgages against it, because a fix is a
bet on where rates are heading, not where they sit today. The base rate tells
you borrowing’s cost now; the SWAP tells you the market’s
expected average ahead. That is why fixed quotes move without any Bank announcement.
Money Pilot - 200+ lenders, zero broker fees, FCA regulated (FRN:
968705).
Ask a commercial mortgage broker why a fixed rate just moved
overnight, and the answer almost never involves the Bank of England making an
announcement. More often than not, it comes down to something quieter and less
headline-friendly: SWAP rates shifting in the financial markets.
They don't get discussed on the news the way the base rate does,
but if you're looking at a fixed-rate commercial mortgage, SWAP rates are
arguably more relevant to your pricing than anything the Bank of England
decides.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
What is a SWAP rate?
A SWAP rate reflects what the financial markets expect average
interest rates to be over a specific future period, commonly two, three, or
five years. Lenders use SWAP rates as the benchmark for pricing fixed-rate
mortgages, because a fixed rate isn't just about where interest rates sit
today, it's a bet on where they're heading over the whole length of the
fix.
In simple terms: the base rate tells you what borrowing costs
right now. A SWAP rate tells you what the market expects borrowing to cost, on
average, over the years ahead.
Why do lenders use SWAP rates instead of just the base
rate?
Because a fixed-rate mortgage locks the lender into a rate for
several years, regardless of what happens to the base rate in the meantime. If
the lender priced a five-year fix purely against today's base rate, and rates
then rose sharply, they'd be stuck lending at a rate that no longer reflects
their own cost of funding.
SWAP rates let lenders hedge against exactly that risk. They
effectively lock in their own cost of funds for the same period they're
offering you a fixed rate, and price your mortgage around that.
How does this actually affect your commercial
mortgage?
If you're looking at a fixed-rate commercial mortgage, the SWAP
rate for that term (say, five-year SWAPs for a five-year fix) is the benchmark
your pricing is built around. When five-year SWAP rates rise, expect fixed-rate
commercial mortgage pricing to follow within days, sometimes even before the
base rate has moved at all.
If you're looking at a variable or tracker commercial mortgage,
SWAP rates matter less directly, since these deals typically track the Bank of
England base rate instead.
Why do SWAP rates sometimes move before the base rate
does?
Because SWAP rates are forward-looking, they reflect what the
market expects to happen, not just what's happening today. If inflation data, a
Bank of England statement, or wider economic news suggests rates are likely to
rise or fall in the future, SWAP rates can move immediately, well before the
base rate itself changes.
This is exactly why fixed commercial mortgage pricing sometimes
shifts with seemingly no obvious trigger. The trigger was in the markets, not
in an interest rate announcement.
Does this mean you should time your application around SWAP
rates?
It's tempting to think you can, but trying to perfectly time a
commercial mortgage application around SWAP rate movements is genuinely
difficult, even for people who watch markets professionally. Rates can move in
either direction with very little warning.
A more practical approach is to keep an eye on the general
trend, and to move when your deal is ready rather than waiting indefinitely for
a theoretically perfect moment that may never arrive.
What should you actually take away from this?
A few practical points:
- Fixed rates track SWAP rates.
Variable and tracker rates track the base rate. Know which one applies to your
deal.
- SWAP rates can move quickly,
sometimes daily, which is why a quote you received last week may no longer be
available today.
- Locking in a rate early, once you're happy with it, protects
you from further SWAP rate movement while your application
progresses.
- A broker who watches this daily
can often flag favourable pricing windows you wouldn't spot on your
own.
The mistake people often make
Borrowers sometimes assume a fixed-rate quote will simply still
be there when they're ready to proceed weeks later. With SWAP rates moving in
the background, that's not guaranteed.
If you've been quoted a rate you're happy with, it's usually
worth asking your broker how that rate can be secured, rather than assuming
it'll wait for you.
The bottom line
SWAP rates are the benchmark lenders use to price fixed-rate
commercial mortgages, reflecting where the market expects interest rates to
average over the term of your fix. They can move independently of, and often
ahead of, the Bank of England base rate, which is why fixed commercial mortgage
pricing can shift with little obvious warning.
Understanding that SWAP rates, not just the base rate, drive
fixed pricing helps explain why the rate you saw mentioned last month might
already be out of date, and why acting once you're happy with a quote is
usually wiser than waiting for a perfect moment.
FAQ
Swap rates commercial mortgages uk - your
questions answered
Because fixed pricing
tracks SWAP rates, which shift daily on market expectations - inflation data,
economic releases, and global moves all feed them. The base rate is a committee
decision eight times a year; SWAPs never stop
trading.
Far less directly -
variable and tracker deals follow the base rate plus margin. SWAPs are the
fixed-rate story, which is why the fix-vs-variable decision is partly a
question of which benchmark you would rather
ride.
Usually less than
borrowers hope - expected cuts are already inside today's SWAP pricing. Fixed
rates move on surprises versus expectations, which is why waiting for announced
cuts to reach fixed pricing so often
disappoints.
The one matching your
fix: two-year SWAPs behind two-year fixes, five-year behind five-year. The gap
between them also tells a story - markets charging more for longer certainty,
or occasionally less.
Cautiously - securing a
product when pricing is acceptable, with the ability to re-broke if it improves
before completion, beats trying to call the bottom. Certainty locked beats
perfection chased.
We watch the pricing that
matters for your case, secure products early with re-broke rights where pricing
improves, and compare the whole market on the day - 200+ lenders, zero broker
fees, FCA regulated (FRN: 968705). Call 020 4634
8617.
Disclosure:
Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone
Finance Group Ltd which is authorised and regulated by the Financial Conduct
Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not
a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You
should always make sure you are able to afford any repayments as late or missed
payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.