HomeArticlesWhat Is a Commercial Mortgage and how does It work in UK?
What Is a Commercial Mortgage and how does It work in UK?
September 08, 2026 10 Min Read
Commercial Mortgage
✅ What is a commercial
mortgage and how does it work?
A commercial
mortgage is a loan to buy, refinance, or release equity from property used for
business purposes - offices, warehouses, shops, restaurants, or your
own trading premises. Unlike residential lending assessed on personal income,
it is built around the property’s commercial use and the income
behind it, with individually priced rates, typically 25–30% deposits,
and terms shaped per deal. Money Pilot arranges them across 200+ lenders at
zero broker fees - FCA regulated (FRN: 968705).
Here's something people often discover the hard way: a
commercial mortgage isn't simply a bigger mortgage, or a more complicated one.
It's a different conversation altogether.
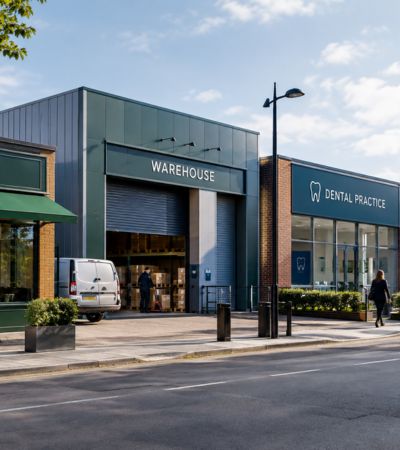
Walk into your local coffee shop, the owner probably has a
commercial mortgage. Drive past a warehouse, commercial mortgage. That dental
practice on the high street, probably a commercial mortgage. The local pub,
quite possibly. If the property is being used for business purposes, there's a
good chance commercial finance is involved somewhere.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
So, what is a commercial mortgage?
A commercial mortgage is a loan used to buy, refinance or
release equity from a property that's used for business purposes. Unlike a
residential mortgage, which is designed for someone buying a home to live in, a
commercial mortgage is built around the property's commercial use.
That could mean you're:
Buying
business premises
Purchasing
an office
Acquiring
a warehouse
Buying
a retail unit
Financing
a restaurant
Purchasing
a medical practice
Buying
a mixed-use building
Refinancing
an existing commercial property
It's less about where you sleep, and much more about where you
work.
How does a commercial mortgage work?
The basic principle is reassuringly familiar. You contribute a
deposit, the lender provides the remaining funds, and you repay the loan over
an agreed period, together with interest. Simple enough.
Where commercial mortgages become more interesting is how
lenders decide whether to lend. With a residential mortgage, the spotlight
usually falls on your income. With a commercial mortgage, lenders often spend
just as much time looking at the business and the property itself.
Can the business comfortably support the borrowing? Is the
property suitable security? Does the transaction make commercial sense? Those
questions matter every bit as much as your personal finances.
Who can apply for a commercial mortgage?
Commercial mortgages aren't just for large companies with glass
offices and impressive reception desks. They're regularly used by:
Sole
traders
Limited
companies
Partnerships
Property
investors
Landlords
Professional
practices
Business
owners
Pension
funds through a SIPP or SSAS
If you're buying a property that generates income or supports a
business, a commercial mortgage could be the right type of finance.
What types of property can be financed?
Almost every type of commercial property has lenders willing to
consider it, including:
Offices
Shops
Warehouses
Industrial
units
Restaurants
Hotels
Guest
houses
Care
homes
Medical
practices
Nurseries
Public
houses
Mixed-use
buildings
Semi-commercial
properties
Some lenders specialise in certain sectors, others have a much
broader appetite. That's why matching the lender to the property often matters
just as much as the interest rate.
How much can you borrow?
That depends on several factors: the property's value, the
strength of the business, the rental income where applicable, your experience,
and how much deposit you're contributing.
Most commercial lenders will lend somewhere between 65% and 75%
of the property's value, although some cases may fall outside those ranges
depending on the circumstances. Commercial lending is rarely a
one-size-fits-all market.
How long does a commercial mortgage last?
Commercial mortgages are long-term loans. Many run between 10
and 25 years, although shorter and longer terms are available.
The right term depends on your objectives. Some borrowers want
the lowest monthly repayments, others prefer to clear the borrowing more
quickly. It's about finding the balance that suits both the business and the
property.
How are commercial mortgages assessed?
Here's where commercial lending starts to differ from
residential borrowing. Lenders don't just ask whether you can afford the
repayments, they ask whether the property itself supports the
borrowing.
For owner-occupied premises, they'll usually assess the
financial strength of the business. For investment properties, they'll look
closely at the rental income. They'll also consider:
The
property's location
The
type of business
Trading
history
Accounts
Deposit
size
Loan-to-value
Credit
history
The
overall quality of the proposal
Commercial lending is as much about judgement as
mathematics.
Is it harder to get a commercial mortgage?
Sometimes. Commercial mortgages involve larger sums of money and
more variables, which naturally means more detailed underwriting. But
"harder" isn't always the right word, it's simply more
bespoke.
A residential mortgage might fit neatly into a computer's
checklist. Commercial lending often involves experienced underwriters making
commercial decisions. That's why two lenders can reach completely different
conclusions on exactly the same application.
The biggest misconception
Many people believe commercial mortgages are only for
experienced investors or large companies. They aren't.
Some of the most common borrowers are people buying the premises
their own business already occupies: a mechanic buying his garage, a pharmacist
buying their pharmacy, a café owner buying the building they've rented for
years. They're not building property empires, they're investing in the place
where they earn their living.
Why use a commercial mortgage broker?
Commercial lenders all have different priorities. One might love
healthcare properties, another may actively seek industrial units. Some focus
on owner-occupied businesses, others specialise in investment
property.
Trying to identify the right lender on your own can be
time-consuming. An experienced commercial mortgage broker understands which
lenders are most likely to support your particular transaction, helping you
avoid unnecessary applications and keeping the process moving.
The bottom line
A commercial mortgage is a long-term loan used to purchase or
refinance property that's used for business purposes. The process shares some
similarities with a residential mortgage, but the way lenders assess
applications is often very different.
They're not simply lending to a person. They're lending against
a business, a property and a commercial opportunity. Get those three things
right, and a commercial mortgage can become one of the most valuable
investments a business ever makes.
Because paying rent to someone else is one thing. Owning the
building your business calls home is something else entirely.
FAQ
What is a commercial mortgage and how does
it work - your questions answered
Business owners buying
their own premises, investors purchasing property to let to businesses, and
anyone financing property whose use is commercial - the coffee shop, the
warehouse, the dental practice, and the pub on the high street are all
commercial mortgage territory.
Around the commercial
case rather than your payslip: the business's accounts and trading performance
for owner-occupiers, or the rental income and tenant strength for investors -
plus the property itself and your deposit.
Plan around 25–30% deposit
for most cases, with rates priced individually per deal rather than from a
published menu - the factors behind that pricing are covered in our companion
guide on how commercial mortgage rates are
determined.
Mixed-use property - the
shop with the flat above - sits in semi-commercial lending, its own market with
its own lenders. See our semi commercial mortgage guide for how that middle
ground works.
Both exist in commercial
lending: capital repayment builds equity over the term, while interest-only
keeps payments lower with the balance repaid at the end - common for investors
planning sales or refinancing. Structure follows your plan for the
property.
Whole-of-market: your
case matched against 200+ lenders' criteria - high street, challenger, and
specialist - at zero broker fees, FCA regulated (FRN: 968705). Call 020 4634
8617 with the property and the plan.
Disclosure:
Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone
Finance Group Ltd which is authorised and regulated by the Financial Conduct
Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not
a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You
should always make sure you are able to afford any repayments as late or missed
payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.