HomeArticlesWhat Is DSCR Commercial Mortgages and Why Does It Matter?
What Is DSCR Commercial Mortgages and Why Does It Matter?
September 14, 2026 8 Min Read
Commercial Mortgage
✅ What is DSCR and why does
it matter for commercial mortgages?
DSCR -
Debt Service Coverage Ratio - measures whether the income a property
or business generates comfortably covers the mortgage repayments, with room to
spare: Net Operating Income ÷ Annual Mortgage Repayments. A property
earning £30,000 against £24,000 of repayments has a DSCR of
1.25 - 25% breathing room. It is the number that decides most
commercial applications, ahead of income or credit score. Money Pilot structures
cases to the DSCR lenders want - 200+ lenders, zero broker fees, FCA
regulated (FRN: 968705).
Ask a first-time commercial borrower what will decide whether
their application succeeds, and most will say their income, or maybe their
credit score. Neither is wrong exactly. Neither is the main event
either.
The number that actually decides most commercial mortgage
applications is one most people have never heard of before they start the
process: the DSCR.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
What does DSCR stand for?
Debt Service Coverage Ratio. It sounds like something from an
accountancy exam, and in fairness, it sort of is. But the idea behind it is
simple enough to explain in one sentence. DSCR measures whether the income a
property or business generates comfortably covers the mortgage repayments, with
some room to spare.
How is it actually calculated?
The formula itself is straightforward:
DSCR = Net Operating Income ÷ Annual Mortgage
Repayments
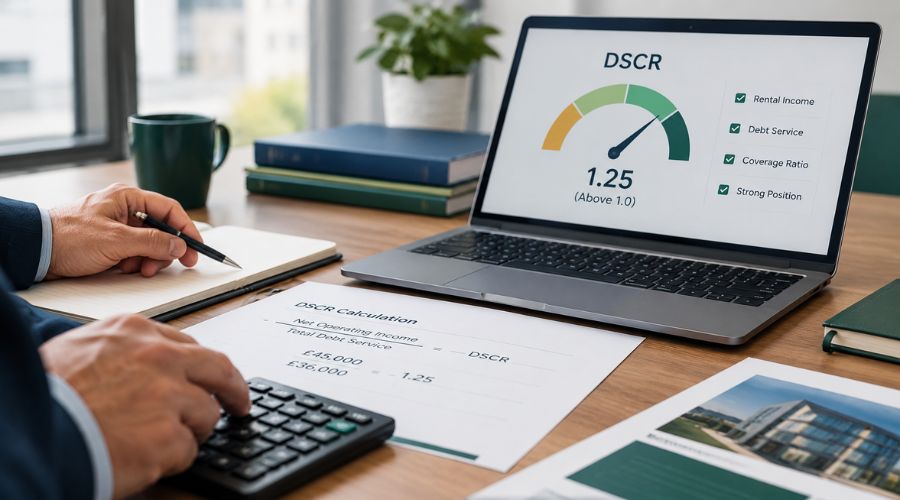
So if a property generates £30,000 a year in rental income, and
the annual mortgage repayments come to £24,000, the DSCR is 1.25. That means
the income covers the debt 1.25 times over, or put another way, there's 25%
breathing room above what's needed to service the loan.
For an owner-occupier buying premises for their own business,
the same principle applies, except the "income" side of the equation
is the business's trading profit rather than rental income.
Why does it matter so much?
Because it answers the one question every commercial lender
cares about most: if things get tight, does this deal survive?
A residential mortgage is largely assessed against your personal
income and outgoings. A commercial mortgage is assessed against the performance
of the asset or business itself. The DSCR is the number that translates
"does this make financial sense" into something a lender can actually
underwrite against.
What DSCR do lenders typically want to see?
Most UK commercial lenders look for a DSCR of somewhere between
1.25x and 1.5x. Below that, and the deal starts to look uncomfortably tight,
there isn't enough of a buffer if income dips or rates rise. Above that, and
the lender gains more confidence, which can also translate into better
terms.
Some lenders will consider deals slightly below 1.25x if other
parts of the application are particularly strong, but it's rarely a comfortable
place to be.
Why the "stress test" matters too
Here's the part that catches people out. Lenders don't just
check your DSCR against today's interest rate, they usually stress-test it
against a higher rate as well, to check the deal would still hold up if rates
increased during the term.
So a deal that comfortably clears 1.3x at today's rate might get
stress-tested against a rate two or three points higher. If it fails that test,
the lender may reduce how much they're willing to lend, ask for a bigger
deposit, or decline the application altogether.
What if your DSCR isn't quite high enough?
This is more common than people expect, and it isn't necessarily
the end of the road. Ways to improve it include:
- Increasing the deposit, which reduces the loan amount and
therefore the repayments
- Extending the mortgage term, which lowers the monthly cost
(though increases total interest paid) (only applies if repaying on a Capital
& Interest basis)
Finding
ways to increase the property or business's income
- Looking at lenders whose criteria are slightly more flexible
on coverage ratios
An experienced broker will often spot which of these levers
makes the difference, rather than the borrower simply being told no.
The mistake people often make
Borrowers frequently walk into a commercial mortgage
conversation focused entirely on the deposit and the interest rate, and are
genuinely surprised when DSCR becomes the sticking point. It's worth
calculating an estimated DSCR before you get attached to a property, not
after.
A gorgeous unit with an excellent price tag is no use if the
numbers behind it don't clear the bar.
The bottom line
DSCR is, without much competition, the single most important
figure in a commercial mortgage application. It tells the lender whether the
income behind the deal can carry the debt comfortably, with enough margin to
survive a bump in the road.
Get your deposit sorted, get your accounts in order, but check
your DSCR before anything else. It's usually the number that decides everything
that follows.
FAQ
What is dscr commercial mortgage - your
questions answered
Net Operating Income ÷
Annual Mortgage Repayments. Rental income (after running costs) for investment
property; trading profit for owner-occupiers buying their own premises. £30,000
income against £24,000 repayments = 1.25.
Comfortably above 1.0 -
income merely equalling repayments leaves no margin. Expectations vary by
lender and case type, which is why knowing each lender's threshold before
applying beats discovering it in a decline.
Because it answers the
lender's real question directly: will this specific loan be serviced by this
specific income, with headroom for voids, cost rises, or rate movement?
Personal income and credit support the case; DSCR is the
case.
The equation has levers:
a larger deposit shrinks the loan and the repayments; a longer term or
interest-only structure lowers the annual debt service; and different lenders
stress the numbers differently - the same case can pass at one lender and fail
at another.
Yes - lenders often
stress-test at rates above today's, so a case that squeaks past at the pay rate
can fail the stressed calculation. Building genuine headroom is what survives
the stress test.
We run the calculation
the way each lender runs it - their stresses, their income definitions - then
structure loan size, term, and repayment type to pass where the pricing is
best. 200+ lenders, zero broker fees. Call 020 4634 8617. FCA regulated (FRN:
968705).
Disclosure:
Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone
Finance Group Ltd which is authorised and regulated by the Financial Conduct
Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not
a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You
should always make sure you are able to afford any repayments as late or missed
payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.
What does Money Pilot do?
Our smart-search engine analyses your requirements — amount, term, business type, and credit profile — then instantly matches them against our panel of 200+ lenders.
Yes — comparing finance options and getting matched with lenders through Money Pilot is completely free, with no obligation to proceed.
Business finance, property finance, bridging loans, commercial mortgages and more — our panel of 200+ lenders covers most funding needs.
Often, yes. Many of our lenders specialise in cases with adverse credit history — our matching engine will surface the right options for your circumstances.
Indicative matches are instant. Full lender decisions typically follow within 24-48 hours, depending on the complexity of your enquiry.
You can complete the whole journey online, but our team is always on hand if you would rather talk it through with a specialist.
Yes, we work with introducing brokers under standard commission terms — get in touch with our team for details.
Three simple steps to get you the funding you need, faster.
1
Submit Enquiry
Complete a fast but in-depth overview of your finance requirements to allow our powerful matching engine to source the right lenders for you.
2
Connect
Engage directly with lenders in real-time, with our friendly advisors always on hand to guide you through every step of the funding journey.
3
Apply
Track your enquiry in real-time and seamlessly move to application — all in one place — getting you to your funds faster and with less hassle.
Get in touch with our team
Get a Quick Quote
Get in touch with our team
Contact Us
Telephone: 02046348617
Email: info@money-pilot.co.uk
Unit 1, Verney House 1B Hollywood Road, London SW10 9HS
Opening Times: 9am - 6pm, Mon - Fri
Company Registration No. 13621432
We use cookies to improve your experience, provide live support, and analyse site traffic. By clicking "Accept All", you consent to our use of cookies.
Cookie Preferences
Select which cookies you want to accept. Essential cookies cannot be disabled.
Required for the website to function securely and save your preferences.
Enables our live chat support (HubSpot) and remembers your session state.
Allows us to measure traffic and see how visitors use the site via Google Analytics.
Used to deliver and track personalized advertisements via Google Ads and Meta.