✅ How does buying a property at auction work in the UK?
You register, review each lot’s legal pack, and bid; at a traditional (unconditional) auction the winning bid exchanges contracts on the spot - you pay a deposit (typically 10%) immediately and must complete, usually within 28 days, or lose it. Modern (conditional) auctions instead give a reservation period (commonly 56 days) in exchange for a non-refundable reservation fee. The discipline: legal pack to a solicitor, viewing done, finance arranged and maximum bid set before auction day. Money Pilot arranges auction-speed funding - 200+ lenders, zero broker fees, FCA regulated (FRN: 968705).
Every buying property at auction guide should open with the sentence that reorders everything else: when the hammer falls, you have exchanged contracts. Not agreed in principle, not subject to survey - legally committed, deposit paid, completion typically 28 days away. Auctions remain one of the best hunting grounds in UK property - honest prices, motivated sellers, stock the open market never shows - but they reward the prepared and quietly confiscate deposits from everyone else. This guide is the preparation.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
How an auction purchase actually runs - hammer to keys
The sequence is unforgiving because it is contractual: catalogue released (usually 2–4 weeks ahead) → legal packs published → viewings → auction day → hammer = exchange → 10% deposit paid immediately → completion deadline - 28 days as the standard, some contracts shorter, some longer. Miss completion and the seller can keep the deposit, resell the property, and pursue costs. Nothing about that timetable flexes for a slow solicitor or a mortgage still in underwriting - which is why every serious bidder finishes this checklist first:
- View the property - auction stock is sold as seen; the price already assumes you looked
- Legal pack to your solicitor - before bidding, not after winning (the red flags below are why)
- Finance arranged to auction speed - a decision in principle in hand before you register to bid
- Maximum bid set in cold blood - including deposit, fees, works and finance costs, written down and obeyed in the room
Auction legal pack red flags UK - where the real price hides
The auction legal pack red flags uk experienced buyers hunt first are the reason some lots look cheap. The pack - title, searches, special conditions, leases, replies to enquiries - is published precisely so that nothing in it can be unwound later. What a good solicitor flags inside 48 hours:
Special conditions - the seller’s quiet surcharges
Buried clauses routinely transfer the seller’s auction fees, searches, arrears or even a percentage “contribution” to the buyer, and can shorten completion below 28 days. The real price of a lot is the hammer price plus its special conditions - always.
Title and tenancy traps
Missing searches (you insure or absorb the risk), restrictive covenants that block your plans, flying freeholds, short leases priced as long ones, and tenancies in situ - sometimes at rents, or on terms, that reshape the investment case entirely. None of these are necessarily deal-killers; all of them are price-changers that must be known before your maximum bid is set.
Conditional vs unconditional auction UK - two different contracts
The conditional vs unconditional auction uk distinction decides what the hammer actually means for you - and the two methods suit different buyers.
How they compare:
- Unconditional (traditional) - hammer = exchange; 10% deposit on the day; completion typically 28 days; maximum certainty, maximum speed required
- Conditional (modern method) - hammer = exclusivity: a non-refundable reservation fee (often around 4 - 5%, frequently on top of the price) buys a reservation period, commonly 56 days, to exchange and complete
- The fee trap - reservation fees usually don’t count toward the price and are lost if you walk; factor them into the true cost before bidding
- Who suits which - cash-ready investors and bridging-backed buyers dominate unconditional rooms; conditional suits buyers needing mortgage timelines - but the fee prices that comfort
- Either way - the legal pack discipline is identical: both methods bind you to what the pack disclosed
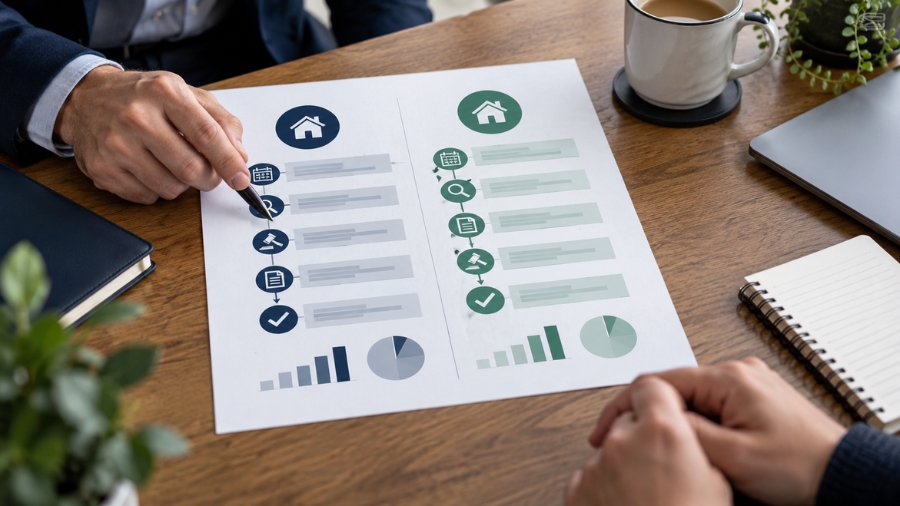
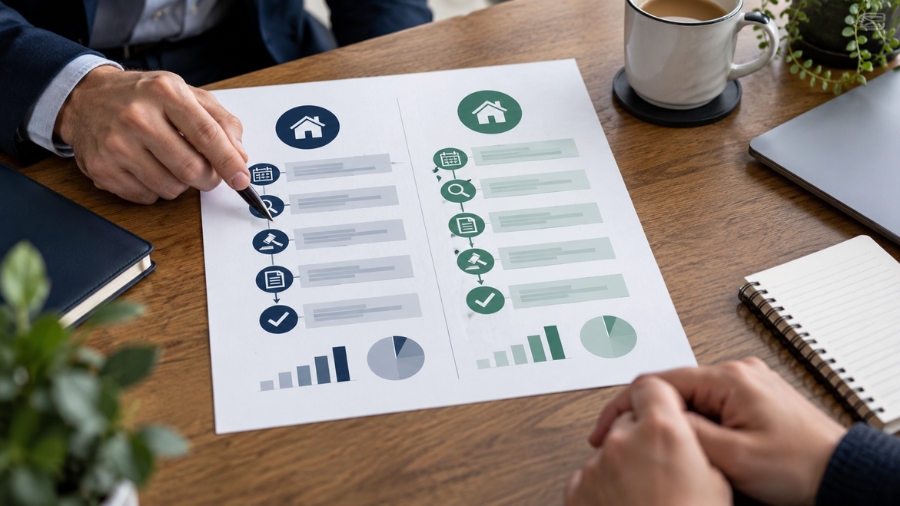
Conditional vs unconditional auction UK — what the hammer means under each method, and what each one costs.
Auction deposit and completion rules UK - the money mechanics
The auction deposit and completion rules uk are brutally simple: win, and 10% of the hammer price leaves your account that day (card or bank transfer - auctioneers rarely take promises), alongside the auctioneer’s admin or buyer’s fee. The remaining 90% is due at completion - the 28-day standard, unless the special conditions say otherwise. Fail, and the cascade is: deposit forfeited, property remarketed, and the contract typically lets the seller claim interest, costs and any shortfall on resale. This is why auction finance is arranged backwards from the deadline: guide prices are marketing, so the funding plan must survive the lot selling 20 - 30% above guide, and the product must complete inside the contract - which in practice means bridging for most non-cash buyers, as standard mortgage timelines simply do not fit.
Having the finance ready - the part that wins auctions
The buyers who win auction rooms are the ones for whom the hammer starts execution, not panic. A pre-auction decision in principle on bridging finance confirms the budget before you bid; completion then runs inside the deadline — auction lots are often uninhabitable or non-standard, exactly what bridging exists for, with costs and mechanics covered in our how to get a bridging loan and bridging loan costs guides. The finance-side sprint - what happens hour by hour after you win - has its own dedicated companion: our 28-days-to-complete finance playbook. Call Money Pilot on 020 4634 8617 before auction day: 200+ lenders, zero broker fees, and a maximum bid you can actually stand behind.