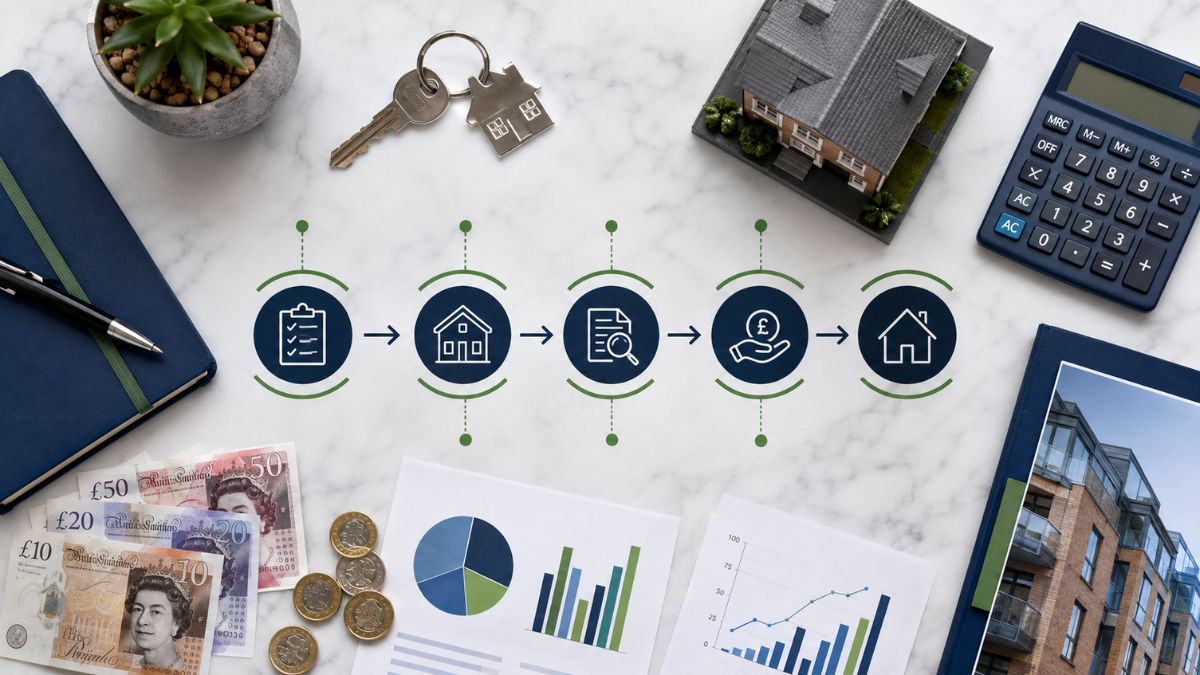
How to get a bridging loan UK - the five steps
Step 1 - Confirm your exit strategy first
Every bridging lender asks the same first question: how will the loan be repaid? This is your exit strategy, and it decides whether your application succeeds. The two standard exits are sale of the property - evidenced by local comparable sales and agent appraisals - or refinance onto a term product such as a buy to let mortgage or commercial mortgage, evidenced by a decision in principle from the refinance lender.
Strong applications arrive with the exit already documented. If your exit is refinance, obtain the DIP before applying for the bridge. If your exit is sale, gather comparables now. A well-evidenced exit unlocks better rates and faster approvals.
Step 2 - Prepare your documents
Bridging lenders underwrite quickly when the file is complete. The bridging loan application process UK lenders run fastest requires:
- Proof of ID and address for all borrowers - plus company documents for SPV or limited company applications
- Security property details - address, purchase price or value, condition, and tenure
- Purpose of funds and a works schedule if you are refurbishing
- Exit evidence - refinance decision in principle or sale comparables
- Assets, liabilities, income, and credit commitments statement
- Solicitor details - instruct a firm experienced in bridging; inexperienced solicitors are the single biggest cause of delay
Step 3 - Get a decision in principle
With the file prepared, a specialist broker approaches the lenders whose criteria match your case - loan size, property type, location, credit profile, and speed required. A decision in principle typically arrives within 2 to 24 hours, setting out the loan amount, rate, term, and conditions. Because bridging lenders vary widely in appetite and pricing, whole-of-market comparison at this stage routinely saves borrowers thousands over the loan term.
Step 4 - Valuation and legal work run in parallel
Once terms are accepted, the lender instructs a valuation of the security property. Many 2026 lenders use desktop valuations for lower-risk cases, cutting days from the timeline; physical inspections remain standard for higher LTVs, refurbishment projects, and commercial security. Simultaneously, your solicitor and the lender’s solicitor progress title checks, searches or indemnity insurance, and the facility agreement. This parallel processing is where bridging speed comes from - on a well-prepared case both complete inside 5 to 10 working days.
Step 5 - Completion and drawdown
When valuation and legals are satisfied, the facility is signed, funds are released to your solicitor, and the purchase completes. From first enquiry to drawdown, a straightforward residential bridge completes in 5 to 14 days. Genuinely urgent cases have completed in 48 to 72 hours where every party moved quickly - fast bridging finance UK specialists exist precisely for these deadline-critical situations.
What do bridging lenders look for in 2026?
Bridging loan requirements UK lenders apply focus on the security and the exit rather than income. Understanding the criteria before you apply lets you target the right lenders first time.
The core bridging loan requirements UK lenders assess:
- Loan to value - most cap at 70–75% LTV on residential security, lower on commercial
- Exit strength - an evidenced, realistic exit matters more than income
- Property quality - standard construction in marketable locations attracts the best terms
- Experience - refurbishment projects are assessed against your track record
- Credit history - adverse credit is considered by specialist lenders where security and exit are strong
Bridging lenders assess the security property, LTV, and exit strategy first — income matters far less than in mortgage underwriting. Money Pilot matches your case to the right lender from 200+ specialists.
Open or closed bridging - which should you apply for?
A closed bridging loan has a fixed repayment date with the exit already contracted - for example, exchange has taken place on the sale of your existing property. Because the lender’s risk is lower, closed bridges price at the cheaper end of the market. An open bridging loan has no fixed repayment date within the maximum term, used where the exit is planned but not yet contracted - a sale not yet agreed or a refinance not yet applied for. Open bridges are priced slightly higher and lenders scrutinise the exit plan more closely.
Most UK bridging in 2026 is open. Apply for a closed bridge only when your exit is genuinely contracted - the pricing advantage is real, but so is the obligation to repay on the fixed date.
How much does a bridging loan cost?
Bridging rates in 2026 typically run from 0.55% to 1.25% per month depending on LTV, security type, and borrower profile - plus arrangement, valuation, and legal fees. For the complete breakdown with a full worked example, read our companion guide: Bridging Loan Costs UK - What You Will Really Pay in 2026.
A specialist broker helps you compare true total cost - not just the headline rate - and structures the interest (serviced, retained, or rolled) to suit your cash flow during the term.
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.