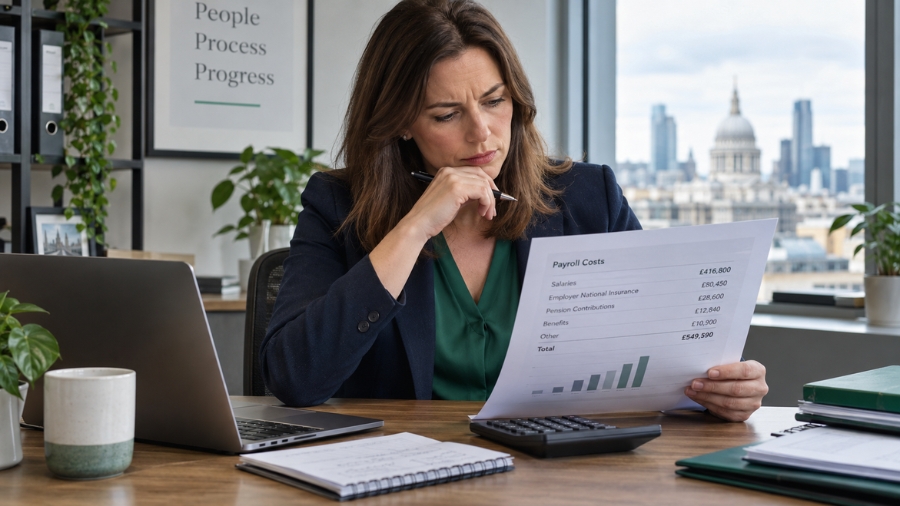
✅ How are SMEs coping with the employers national insurance increase?
By counting it honestly first: at 15% from a £5,000 threshold, a £30,000 employee now costs about £3,750 in employer NIC against roughly £2,884 under the old rules - ~£866 more per employee, per year; ten staff is roughly £8,700 of new annual cost. The offsets: the Employment Allowance doubled to £10,500 with its eligibility cap removed (the smallest employers can be net better off), salary-sacrifice pensions, and hiring-structure choices. The remainder is a working-capital problem - and that is financeable. Money Pilot - 200+ lenders, zero broker fees, FCA regulated (FRN: 968705).
The employers national insurance increase impact stopped being a Budget headline and became a standing order: since April 2025, employer NIC runs at 15% (up from 13.8%) and starts at just £5,000 of salary (down from £9,100) - a double hit that lands on every payslip a business funds. Eighteen months on, the pattern among SMEs is consistent: the cost was absorbed, the cash buffer absorbed it, and 2026’s job is rebuilding that buffer deliberately rather than living without it.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
Counting the hit - what the rise actually costs your payroll
The arithmetic per employee: employer NIC = 15% of everything above £5,000. Worked against the old regime (13.8% above £9,100):
- £25,000 salary - now £3,000 vs £2,194 before: +£806 a year
- £30,000 salary - now £3,750 vs £2,884: +£866
- £45,000 salary - now £6,000 vs £4,954: +£1,046
- The structural sting - the threshold drop taxes the first pound of part-time and entry-level pay hardest: labour-heavy, lower-wage sectors (hospitality, care, retail) absorbed the biggest proportional hit
- Ten-person rule of thumb - a typical mixed payroll of ten carries roughly £8,000–£10,000 of new annual cost before any offsets
Employment allowance changes UK - the offset that got bigger
The employment allowance changes uk are the rise’s deliberate counterweight: the allowance doubled to £10,500 a year off the employer NIC bill, and the old £100,000 eligibility cap was removed, so established SMEs qualify again. The distribution effect is worth internalising - a micro-employer with three or four modest salaries can find the enlarged allowance swallows the entire increase (some are genuinely better off), while a twenty-person employer burns through £10,500 in weeks and carries the rest. Claim it in your payroll software (it is a claim, not an automatic credit), check connected-company rules where you run multiple entities, and re-check eligibility annually - the number of SMEs simply not claiming remains one of accountancy’s quiet scandals.
Offset employer NI costs UK - the levers that are actually legal and real
The offset employer ni costs uk conversation separates into structural levers (real, compounding) and false economies (expensive later).
The levers in order of value:
- Salary-sacrifice pension contributions - the biggest clean win: sacrificed salary avoids employer NIC entirely at 15%, so a well-adopted scheme recovers a meaningful slice of the rise while improving staff pensions
- Claim the full Employment Allowance - £10,500, eligibility now broad; verify it is actually switched on in payroll
- Benefits restructuring - cycle-to-work, EV schemes and similar sacrifice arrangements carry the same NIC logic at smaller scale
- Hiring-structure honesty - apprenticeship NIC reliefs and genuine self-employment where genuine; disguising employment is not an offset, it is a future HMRC bill
- Price and productivity - the uncomfortable lever most actually pulled: the NIC rise travelled into prices, automation decisions and leaner rotas across 2025/26
Offset employer NI costs UK - structural levers first, false economies never.
NIC rise cash flow planning SMEs - rebuilding the buffer it consumed
Nic rise cash flow planning smes comes down to recognising what actually happened: a permanent, payroll-shaped increase in monthly outgoings was funded, in most small businesses, by running the cash buffer thinner. Eighteen months of that leaves firms technically profitable and practically fragile - one slow-paying customer from a crunch. The rebuild is working-capital engineering: a 13-week cash flow forecast that shows the payroll peaks honestly; a committed facility sized to them - a revolving credit facility beats an overdraft that can vanish at renewal; invoice finance where the real gap is customers paying in 60 days while payroll leaves in 30 (the full menu in our working capital guide); and refinancing any expensive stop-gap debt the 2025 adjustment left behind. The error to avoid is treating a structural cost rise as a temporary one - funding permanent outgoings on emergency money is how margin quietly dies.
The 2026 posture - planned resilience over absorbed shock
The businesses handling the employers national insurance increase impact best in 2026 share a posture: the cost is counted per head and priced into quotes; the allowance and sacrifice schemes are maximised; the cash buffer is rebuilt to a stated number of weeks; and the working-capital line is arranged before it is needed - committed facilities are cheapest exactly when you can prove you don’t desperately need them. Money Pilot arranges that resilience layer - facilities, invoice finance, refinancing - across 200+ lenders at zero broker fees. Call 020 4634 8617 with the payroll number and the forecast. FCA regulated (FRN: 968705).