How revolving credit works UK - the mechanics
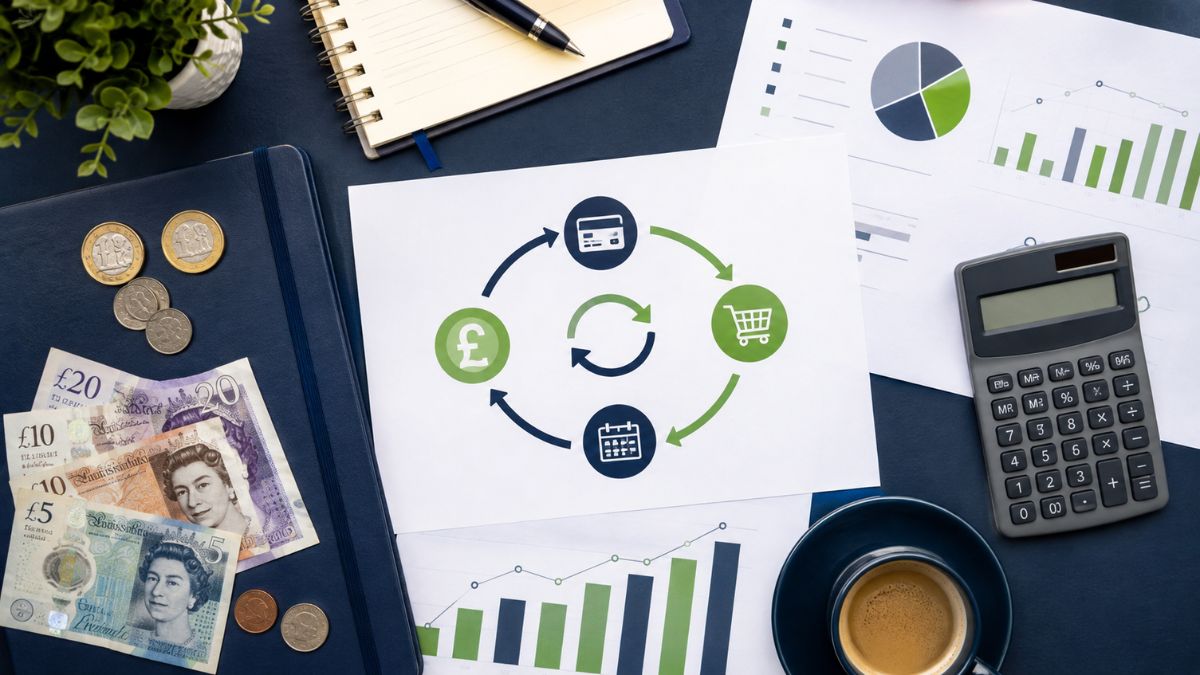
How revolving credit works UK wide follows one loop. The lender agrees a limit against your trading profile. You draw any amount up to it - same-day in most 2026 platforms - and interest accrues daily on the drawn balance only. Repay from customer receipts whenever cash allows, and the repaid amount is immediately redrawable. The draw down repay redraw UK cycle can run weekly, monthly, or seasonally; the facility simply mirrors the shape of your cash flow.
- Limit - sized on turnover and cash generation, commonly 1–2 months of revenue
- Drawings - on demand via platform or request, typically same-day
- Interest - daily, on drawn funds only; nothing drawn, nothing charged (bar the commitment fee)
- Repayment - flexible; minimum interest servicing monthly, capital whenever you choose
- Reviews - annually or semi-annually; well-conducted facilities grow with the business
Worked example - the seasonal wholesaler
A giftware wholesaler with £180,000 monthly average sales holds a £250,000 RCF. August–October it draws £220,000 to build Christmas stock; November–January receipts repay it in full; February–July the facility sits untouched at a small commitment fee. Interest cost for the year: roughly £7,500 on the drawn period - against £22,000+ if the same peak were funded by a £250,000 term loan carrying interest all year. The facility charges for the shape of the need, not the size of the limit.
Business credit line UK - RCF vs overdraft vs term loan
A business credit line UK borrowers choose sits between two older tools - and beats each on its weakness.
The three-way comparison:
- Versus overdrafts - RCF limits are larger, committed for the term (not repayable on demand), and actually available: the overdraft market has spent a decade shrinking
- Versus term loans - loans charge interest on the full sum from day one; RCFs charge only on funds out, and repaying early costs nothing
- Versus cards - cards cap smaller and price higher past the free window; RCFs fund invoices, wages, and transfers cards cannot touch
- The natural stack - card for the 56-day float, RCF for the breathing layer, term debt for permanent capital
- The wrong use - a permanently maxed RCF is a term loan wearing the wrong price tag: refinance it
Business credit line UK - committed availability beyond overdrafts, pay-for-what-you-use beyond loans, and scale beyond cards.
What it costs in 2026
- Interest - typically 8%–15% annually on drawn funds, priced on trading strength and conduct
- Commitment fee - commonly 0.5%–2% a year on the unused limit: the price of guaranteed availability
- Arrangement - 1%–2% on setup with some providers; waived by several platform lenders
- Security - smaller facilities on PGs and a debenture; larger limits may take specific security
- The true comparison - annual cost at your drawing pattern, not the headline rate: a 12% RCF drawn three months a year beats a 9% loan drawn twelve
Who qualifies - and how to run one well
Lenders want 12–24 months of trading, turnover from roughly £200,000, and bank statements showing genuine cash flow rhythm - the product funds breathing, so they look for breath. Adverse credit narrows pricing but rarely closes the market. Running it well is three habits: draw for identified needs with a repayment source in view, not for drift; touch zero regularly - facilities that clear periodically renew easily and grow at review; and pair it correctly - the RCF handles timing, while sustained needs move to invoice finance against the ledger or term debt, and the facility itself sits beside - not instead of - the card programme’s free float.
Covenants and reviews - reading the small print that matters
Two contract clauses deserve attention before signing. First, clean-down requirements: some facilities require the balance to touch zero for a set period each year - reasonable for seasonal borrowers, painful for steady ones, so match the clause to your cycle. Second, review and repricing rights: know whether the lender can cut the limit at review, what notice applies, and what conduct triggers early review. Platform lenders tend to be mechanical (limit follows the data); bank facilities tend to be discretionary. Neither is wrong, but a business relying on the limit for committed orders should know which it holds. A broker negotiates both clauses at the outset - the moment of maximum leverage - rather than at first renewal.
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.