HMO investment strategy UK - where the return comes from
The economics are simple: renting a property by the room prices each room against the sharer market rather than the whole-house market. A four-bed house letting at £1,300 as a family home might achieve £550–£650 per room to four or five sharers - £2,200–£3,000 per month from the same building. The uplift funds the extra costs of the model (bills, licensing, management, higher maintenance) and still leaves net income far ahead.
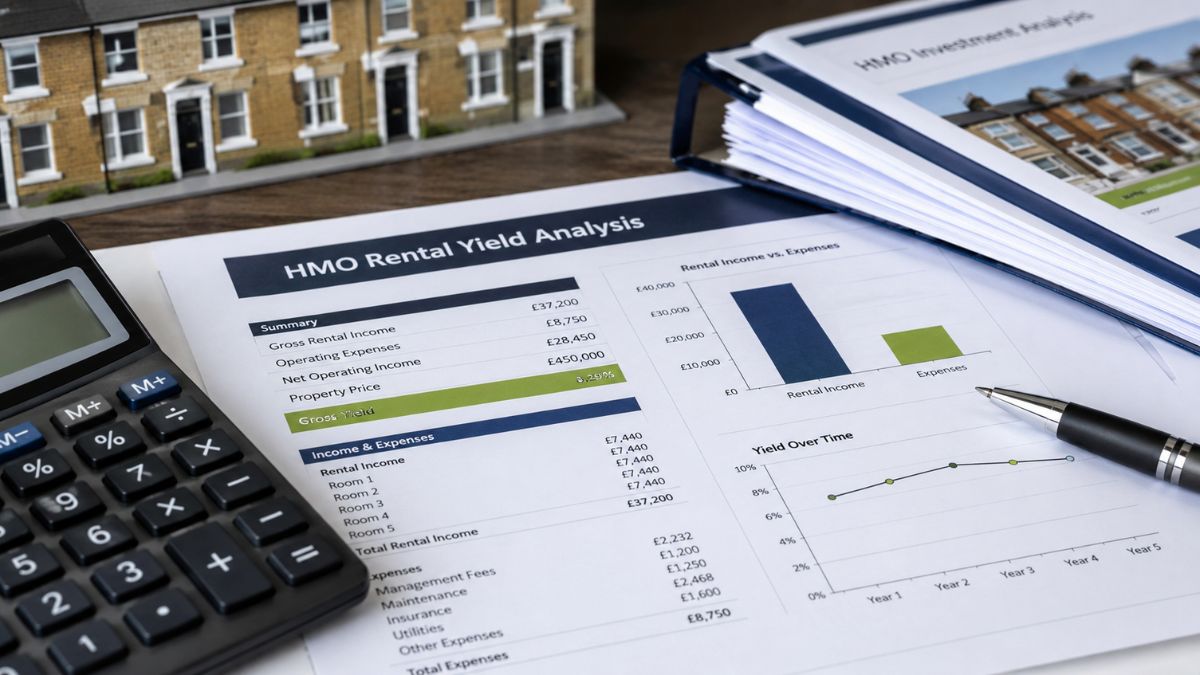
HMO rental yields UK wide in 2026 typically run 8–12% gross in strong sharer markets - university cities, hospital catchments, and employment hubs - against 5–6% for comparable single lets. The strategy’s discipline is protecting that spread: every void room, every compliance failure, and every management shortcut eats directly into it.
HMO vs single let UK - the honest comparison
The hmo vs single let UK decision is a trade of income against simplicity:
- Income - HMOs typically produce 1.7–2.3× the gross rent of the same property as a single let
- Costs - bills-inclusive letting, licensing, and management take 30–40% of gross versus 15–20% for single lets
- Voids - room-level voids are frequent but partial; a single let void is total
- Management - five tenancies, five personalities, and shared spaces need active management or a specialist agent at 10–15%
- Regulation - licensing and standards apply (see our full guide to HMO licensing rules UK)
- Exit - HMOs sell to investors on yield; single lets sell to the whole market on comparables
On £250,000 deployed, a well-located HMO producing 10% gross and ~6.5% net beats the single let’s ~4% net decisively - provided the operator does the work the premium pays for.
HMO property investment returns UK - what drives the top quartile
HMO property investment returns UK operators achieve vary enormously. The top quartile share identifiable habits - and none of them is luck.
What separates the best-performing HMOs:
- Location chosen on sharer demand data - graduate retention, hospital and employer catchments - not on cheap purchase price
- Six or more lettable rooms - fixed costs spread further and licensing effort is rewarded
- En-suites and quality finishes - £75–£125 per room premium and measurably lower churn
- Professional tenant profile with 12-month terms - students and professionals rarely mix well in one house
- Systemised management - digital rent collection, maintenance reporting, and quarterly inspections
HMO property investment returns UK top operators achieve come from demand-led locations, scale per property, quality rooms, and systemised management.
Building the strategy - four decisions before you buy
1. Tenant market first
Choose students, young professionals, or key workers before choosing a property - each demands different locations, room specs, and tenancy structures. Professionals are the 2026 growth market: longer stays, bills-inclusive expectations, and willingness to pay for en-suite quality.
2. Article 4 check before offer
In Article 4 areas, converting a family home (C3) to a small HMO (C4) needs planning permission - and existing licensed HMOs in those areas carry scarcity value. Buying an established HMO in an Article 4 zone buys a moat; buying a C3 to convert there buys a planning gamble.
3. Buy on room economics
Underwrite every purchase on achievable room rents, realistic bills, licensing costs, and 8–10% voids - not on the agent’s gross yield claim. If the deal only works at 100% occupancy, it does not work.
4. Decide the exit at entry
Investor-market exits value the income stream; owner-occupier exits value the house. Six-bed conversions with stud walls sell only to investors - price that in when you buy.
Financing the strategy
Specialist HMO finance is assessed on aggregate room income - typically at 70–75% LTV with ICRs of 130–170% on the room-by-room rent, which usually supports more borrowing than a single-let valuation of the same building. The classic build route runs: bridging finance to buy and convert, licence during works, then refinance onto an HMO mortgage at the uplifted commercial valuation - recycling capital into the next project. Limited company ownership dominates new HMO purchases for the tax reasons covered in our limited company buy to let UK guide.
Strategy mistakes that erase the HMO premium
- Buying on gross yield claims - agents quote 12% gross; your appraisal must survive on 6% net
- Skipping the Article 4 check - an unconvertible C3 in a restricted zone is just an overpriced house
- Under-speccing rooms - budget finishes attract churn tenants; churn is the silent killer of net yield
- Self-managing at scale without systems - three HMOs run on spreadsheets and goodwill; ten do not
- Ignoring licensing costs in the appraisal - fees, works to standards, and renewal all belong in the numbers
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.