HMO licensing rules UK - the three regimes
1. Mandatory HMO licensing
Mandatory HMO licensing UK wide applies to any property occupied by five or more people forming two or more households who share facilities such as a kitchen or bathroom. There is no storey requirement - flats, bungalows, and converted buildings are all caught. Every mandatory HMO needs a licence from the local council before it operates, held by the person in control (usually the landlord), lasting up to five years per property.
2. Additional licensing
Councils can designate additional licensing schemes covering smaller HMOs - typically three or four sharers - across all or part of their area. Hundreds of councils now run such schemes, and they change: an unlicensed three-bed sharer house can become licensable overnight when a scheme starts. Checking the council’s current designation is a standing task for every HMO landlord, not a one-off.
3. Selective licensing
Selective licensing applies to all private rentals - not just HMOs - in designated areas, usually targeting low-demand or high-antisocial-behaviour zones. If your HMO sits in a selective area and is below HMO thresholds, it still needs a selective licence.
HMO licence requirements UK - what you must satisfy
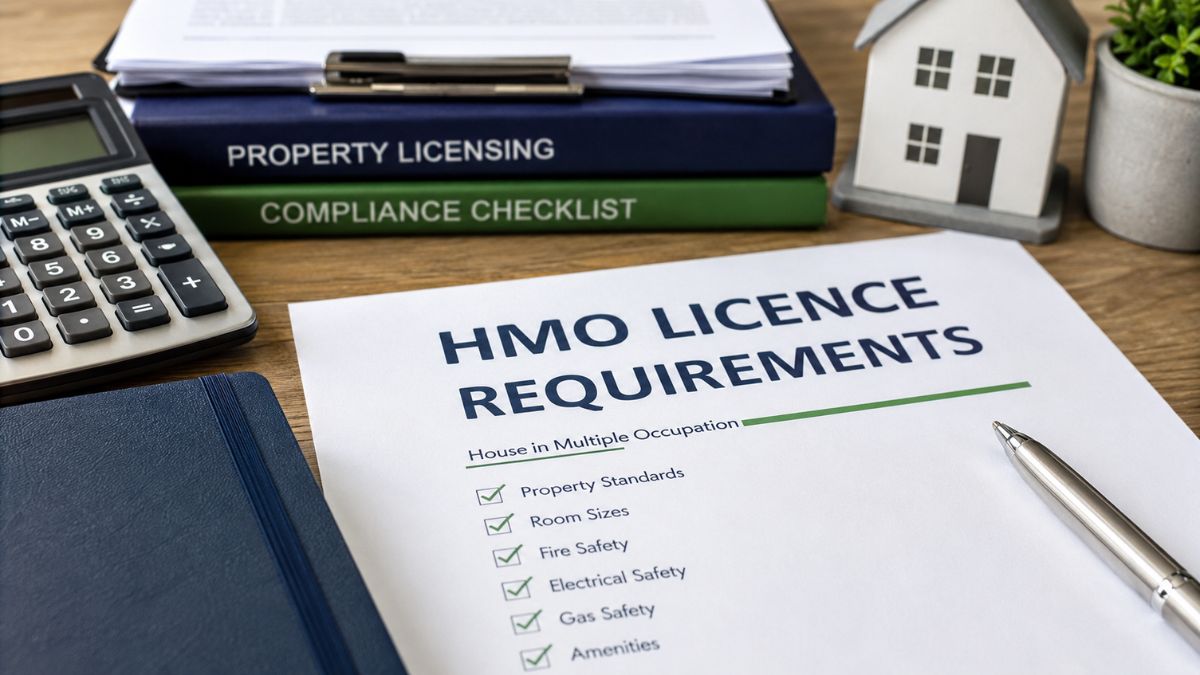
The hmo licence requirements UK councils apply combine national minimums with local conditions:
- Minimum room sizes - 6.51m² for one adult, 10.22m² for two; rooms below 4.64m² cannot be slept in
- Amenity ratios - adequate kitchens, bathrooms, and WCs for the number of occupants (councils publish exact ratios)
- Fire safety - interlinked detection, fire doors, protected escape routes, and often emergency lighting
- Gas and electrical safety - annual gas certificate and 5-yearly EICR, supplied to the council
- Fit and proper person - the licence holder must pass the council’s character test
- Management standards - waste arrangements, maintenance, tenancy management, and occupancy limits set in the licence
HMO regulations landlords UK must not miss beyond licensing
HMO regulations landlords UK wide face extend past the licence itself - several apply to every HMO regardless of size or licensing status.
Compliance that applies even to unlicensed HMOs:
- The Management of HMOs Regulations - duties on repair, cleanliness, and safety with criminal penalties
- Planning: Article 4 areas remove permitted development rights from C3 to C4 - check before you buy
- Deposit protection and prescribed information for every tenancy
- Right to Rent checks on all adult occupants
- EPC minimum standards and smoke/CO alarm rules
HMO regulations landlords UK must meet run beyond licensing - management regulations, Article 4 planning, and tenancy compliance apply to every HMO.
Penalties - what non-compliance actually costs
- Unlimited fines on conviction for operating an unlicensed licensable HMO
- Civil penalties up to £30,000 per offence as an alternative to prosecution
- Rent repayment orders - tenants can reclaim up to 12 months’ rent
- Banning orders and entry on the rogue landlord database for serious offenders
- Section 21 invalid - you cannot serve notice while unlicensed, and mortgage terms are usually breached too
Licensing and your HMO mortgage
Lenders treat the licence as fundamental: HMO finance offers are conditional on a valid licence (or a submitted application) matching the occupancy, and operating outside licence conditions is a breach of mortgage terms. When buying, lenders expect the licence application to be lodged at completion; when refinancing, the licence must match how the property is actually let. A specialist broker sequences the licence and the mortgage so neither blocks the other - and for investors weighing whether the compliance load is worth it, our companion guide on HMO investment strategy UK sets out the returns side of the equation.
Renewals, variations, and buying a licensed HMO
Licences are property- and holder-specific: they do not transfer on sale, so when you buy a licensed HMO you must apply for your own licence from day one of ownership - the seller’s licence dies at completion. Renewals should be lodged well before expiry (many councils treat a duly-made renewal as continuing cover), and any material change - more occupants, room reconfigurations, a new managing agent - needs a licence variation rather than silence. Diarise expiry dates across the portfolio; an expired licence is legally identical to no licence at all.
Getting licensed - the practical sequence
- 1. Check the council’s current mandatory, additional, and selective designations for the exact address
- 2. Confirm planning position - C4 use or sui generis for larger HMOs, and any Article 4 direction
- 3. Measure rooms and amenities against the council’s published standards before committing
- 4. Apply with certificates, floor plans, and the fee - keep proof of submission
- 5. Implement any licence conditions within the stated deadlines and diarise renewal
Disclosure: Money Pilot Ltd (FRN: 968705) is an Appointed Representative of Yellow Stone Finance Group Ltd which is authorised and regulated by the Financial Conduct Authority (FRN: 814533). Yellow Stone Finance Group Ltd is a credit broker not a lender. Money Pilot Ltd is Registered in England and Wales No: 13621432. You should always make sure you are able to afford any repayments as late or missed payments can affect your credit rating and access to future finance.
YOUR PROPERTY MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON A MORTGAGE OR ANY OTHER DEBT SECURED ON IT.