✅ How does the permanent mortgage guarantee scheme work?
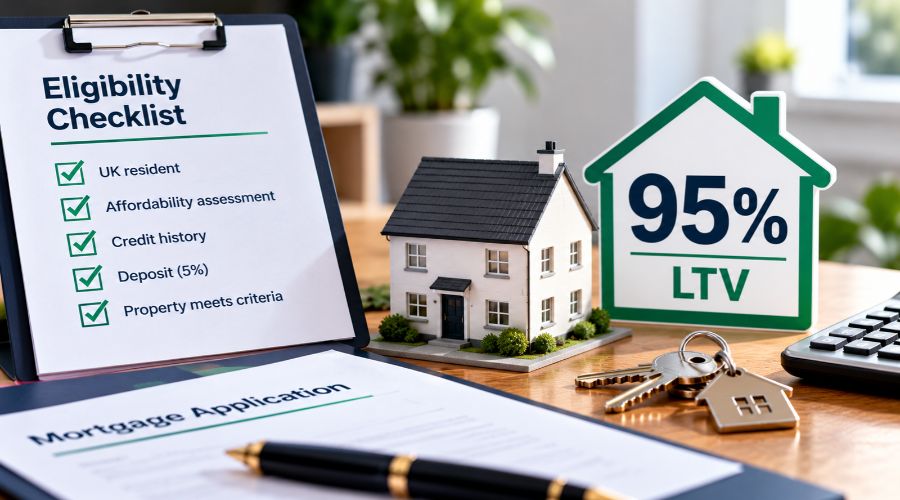
The mortgage guarantee scheme 2026 — branded Freedom to Buy — made government backing for 95% mortgages permanent from July 2025, replacing the temporary scheme that kept expiring and being extended. The mechanics: you provide a deposit as small as 5%; the lender advances up to 95% of the price; and the government insures the lender against a portion of its losses if the loan defaults. Crucially, the guarantee protects the lender, not you — you remain fully liable, and your home is at risk if you don’t keep up repayments. It’s open to first-time buyers and home movers across the UK. The catch: scheme deals aren’t always the cheapest 95% deals on the market. Money Pilot compares both — 200+ lenders, zero broker fees, FCA regulated (FRN: 968705).
The mortgage guarantee scheme 2026 story is really the end of a long game of political hokey-cokey: after years of the temporary scheme lurching from deadline to deadline, the government confirmed a permanent successor — Freedom to Buy — running since July 2025. Permanence matters more than it sounds: lenders build lasting product ranges around schemes they trust to still exist next year, and buyers can plan a purchase without racing an expiry date. But a government badge doesn’t make a deal good. This guide explains how the scheme works, the rules that decide who qualifies, and the honest comparison every 5%-deposit buyer should run before signing anything.
Bank of England held base rate at 4.25% in June 2026 — waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months — confidence remains strong.
Freedom to buy scheme explained — the mechanics behind the badge
The freedom to buy scheme explained in one sentence: the government sells lenders insurance against losses on high-LTV loans, which makes lenders willing to offer 95% mortgages they might otherwise ration. Under the previous scheme the guarantee covered up to 15% of the purchase price and homes up to £600,000; the permanent scheme follows the same blueprint, with lenders paying for the guarantee and setting their own product terms within it.
What that means in practice:
- Your deal looks normal — you apply, pass affordability and credit checks, and repay exactly as on any mortgage; the guarantee operates invisibly between lender and government
- The guarantee is not a subsidy — it doesn’t reduce your rate, your deposit or your liability; 95% LTV pricing still carries a premium over 90% and below
- Standard underwriting applies — repayment basis, income rules and credit standards are the lender’s own; the scheme widens availability, not criteria
- Negative equity risk is yours — with 5% equity, a modest price dip puts you underwater; fine if you stay put, painful if you must sell early
95 percent mortgage support rules — who qualifies and who doesn’t
The 95 percent mortgage support rules are broader than most buyers assume — this was never a first-time-buyer-only scheme. Eligible borrowers include first-time buyers and home movers across the UK, buying a home to live in. Where buyers trip up is on the exclusions and practical limits: the scheme is for residential purchases, not buy-to-let or second homes; individual lenders layer their own restrictions on top, commonly around new-build flats, construction types and maximum loan sizes; and price caps and product terms are set by each lender within the scheme framework — so two “scheme” deals can look quite different. Check the current caps and criteria with a broker rather than assuming last year’s rules.
And the question nobody asks often enough: do you even need the scheme? Plenty of lenders offer 95% mortgages entirely outside it, and those deals are sometimes cheaper — the scheme’s job was to make high-LTV lending normal again, and it has partly succeeded itself out of exclusivity. The badge on the product matters far less than the rate, fees and flexibility behind it.
First time buyer schemes 2026 — the full menu beyond the guarantee
The first time buyer schemes 2026 landscape is wider than one guarantee scheme — the right answer is often a combination, and sometimes none of them.
Compare against:
- 95% deals outside the scheme — often the direct rival; sometimes cheaper, identical in experience
- Lifetime ISA — the 25% government bonus on savings up to £4,000 a year remains the best “free money” for deposits, within its price limits
- Shared ownership — buy a share, pay rent on the rest; smaller deposit still, but layered costs deserve scrutiny
- Joint borrower sole proprietor — family income boosts affordability without co-ownership; a specialist-lender strength
- Deposit Unlock and builder schemes — new-build routes where the guarantee scheme's lender criteria are tightest
Who it genuinely helps — and the honest verdict
The scheme genuinely helps the buyer with solid income, clean credit and a deposit stuck at 5% — typically renters whose payments prove affordability but devour saving capacity. It helps home movers with thin equity more than the headlines suggest. And permanence helps everyone, because stable lender appetite at 95% LTV — reinforced by a growing lending market — keeps that end of the market competitive year-round.
It doesn’t help the buyer whose real problem is affordability rather than deposit — a guarantee doesn’t stretch income multiples. It doesn’t help landlords or second-home buyers, who are excluded. And it may not be the best deal even for its target buyer, which is why the only sensible approach is a whole-of-market comparison: scheme deals, non-scheme 95% deals, and the scheme-specific routes side by side. That comparison is exactly what we do — across 200+ lenders, with zero broker fees.