✅ How do you finance a multi unit freehold block in the UK?
Through a specialist multi unit freehold block mortgage - buy-to-let-style lending built for a single freehold containing multiple self-contained flats. Lenders assess the aggregate rental income across all units, typically lend up to around 75% loan-to-value, and value the block either on an investment basis or as the sum of its parts, depending on size and lender. Mainstream single-let products do not fit; the MUFB market is specialist and broker-led. Money Pilot - 200+ lenders, zero broker fees, FCA regulated (FRN: 968705).
A multi unit freehold block mortgage finances one of the most quietly favoured assets in UK residential investment: a single freehold title containing several self-contained flats, owned and let by one landlord. No leases to anybody else, no service-charge politics, no managing agent you did not choose - one building, one owner, several rents. Investors walk past MUFBs every day without clocking them; specialist lenders, meanwhile, have built entire product ranges around them.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
What counts as a multi unit freehold block - and what doesn’t
The definition is tighter than it sounds: multiple self-contained units - each with its own entrance, kitchen and bathroom - held on one freehold title with no long leases granted on the individual flats. The moment a flat has been sold off on a lease, the building stops being a pure MUFB. Classic examples:
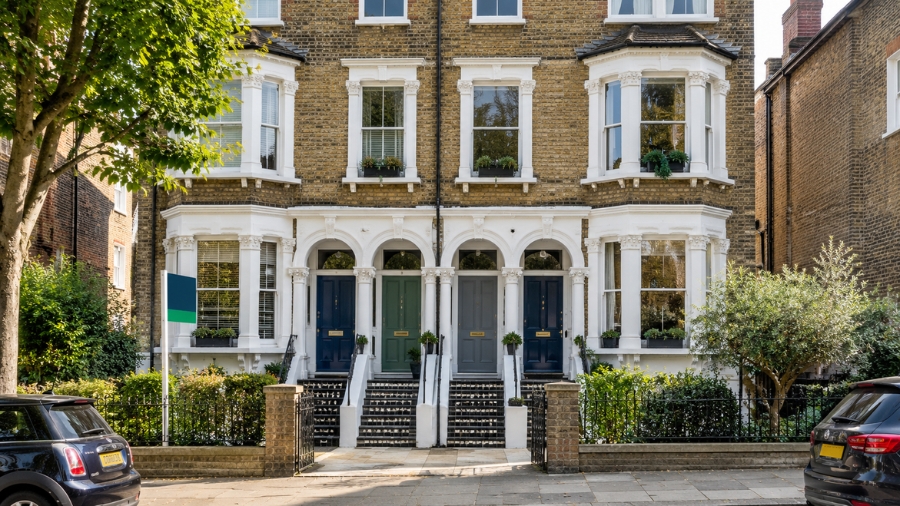
- The converted Victorian house - a large terrace split into three or four self-contained flats, never sold off individually
- The purpose-built small block - four to ten flats built as rentals and kept on one title
- The house with a granny annexe - at the smallest end, two self-contained units on one title can already qualify
- The mixed block above commercial - flats over a shop push the case toward semi-commercial territory instead - a different lender pool
Self-containment is the line that matters most. Rooms sharing a kitchen are an HMO, not a MUFB - and the two are valued, licensed and financed differently, which is exactly where the comparison below earns its place.
MUFB valuation method UK - the question that decides your loan
The mufb valuation method uk lenders apply is the single biggest variable in how much you can borrow. Two bases exist, and the gap between them can be six figures on the same building.
Aggregate basis - the sum of the parts
Smaller blocks are often valued as the total of the individual flat values, as if each could be sold separately. On a converted house of three flats in a street where flats sell well, aggregate value frequently exceeds what the building would fetch as one lot - generous for the borrower, which is why many lenders cap or haircut it.
Investment basis - the block as an income machine
Larger blocks — typically from around six units upward, though every lender draws the line differently - are more often valued on investment basis: the rental income capitalised at a market yield. That number can sit below aggregate value, and your real loan-to-value moves with it. Knowing which basis a lender instructs before application is a genuine broker edge - the same block can support very different loans at two different lenders simply because of the valuation instruction.
Why lenders quietly love MUFBs
Speak to specialist underwriters and the affection is consistent - the MUFB risk profile solves problems other assets create.
The underwriting logic:
- Diversified income on one loan - four flats means a void hits 25% of income, not 100%; single-let risk without single-let fragility
- One borrower, one title, no leasehold layer - no ground rents, no service-charge disputes, no third-party freeholder to underwrite
- No mandatory licensing - self-contained flats sidestep HMO licensing in most cases (selective schemes aside), removing a compliance variable lenders must otherwise police
- Standard tenants on standard ASTs - family and professional lets, longer tenancies, lighter management than room-by-room
- A break-up exit in reserve - the option to lease and sell flats individually later underpins recovery value
MUFB valuation method UK — aggregate basis vs investment basis, and why the instruction decides the loan.
Block of flats investment finance UK - LTVs, stress tests and the lender pool
Block of flats investment finance uk runs on buy-to-let mechanics scaled up: expect maximum loan-to-value around 75% for strong cases, interest cover stress-tested on the aggregate rent across all units, and pricing a notch above vanilla single-let reflecting the specialist assessment. The lender pool is the defining feature - this is specialist and challenger territory, largely broker-distributed, with high-street names mostly absent. Unit count moves appetite: plenty of lenders are comfortable to six units, fewer beyond ten, and large blocks shade toward commercial investment underwriting. Limited company ownership is routine - the same SPV logic covered in our limited company buy-to-let guide applies, and portfolio landlords should expect whole-portfolio review under the PRA portfolio rules once they hold four or more mortgaged properties.
MUFB vs HMO returns UK - the honest comparison
The mufb vs hmo returns uk question is really yield versus workload. A well-run HMO typically out-earns a MUFB on gross yield - room-by-room letting aggregates higher, as our HMO investment strategy guide sets out. The MUFB answers back on everything else: no licensing in most cases, longer tenancies and lower churn, lighter management, cheaper running costs (tenants hold their own utility accounts), broader lender choice, and a cleaner exit - blocks sell to other investors or break up into flat sales, while large HMOs sell mainly to other HMO operators. Net-net: the HMO usually wins the spreadsheet, the MUFB usually wins the quiet life - and in strong rental areas (see our rental yield areas guide) the gap narrows enough that many portfolio landlords deliberately hold both.
Financing your MUFB - the practical route
Prepare the schedule of units (sizes, ASTs, rents), evidence self-containment, and let the broker match unit count and valuation basis to the right lender before anything is submitted - sequencing that routinely changes the loan by more than any rate negotiation. Purchases, refinances and equity release across blocks all run through our residential investment finance desk: 200+ lenders compared, zero broker fees, and the valuation-basis question answered before it can ambush the deal. Call 020 4634 8617.