✅ How much does a property refurbishment cost in the UK?
As 2026 planning bands per square metre of floor area: light refurbishment (decorating, kitchens, bathrooms, no structural work) commonly runs around £600–£900/sqm; medium schemes (full rewires, re-plumbs, layout tweaks) around £900–£1,400/sqm; heavy or structural refurbishment (extensions, conversions, structural alterations) £1,500 -£2,400+/sqm. Bands, not quotes - spec, region and building condition move them - and every professional budget adds 10–15% contingency. Money Pilot funds refurbs across 200+ lenders at zero broker fees - FCA regulated (FRN: 968705).
Property refurbishment costs uk conversations usually start in the wrong place: a finished-room Pinterest board and a number someone’s brother-in-law paid in 2019. Professionals start somewhere else entirely - cost per square metre, a defined scope, a contingency they expect to spend, and a lender-ready split between light and heavy works, because that single definition decides which finance the project can use. This is the 2026 budgeting framework, numbers included.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
Refurbishment cost per square metre UK - the 2026 bands in detail
Refurbishment cost per square metre uk is how builders quote, lenders assess and professionals compare - so budget in it from day one. A 90 sqm three-bed terrace at the bands above: a light cosmetic scheme plans at roughly £55k–£80k, a full medium refurb £80k–£125k, and heavy works beyond. Where budgets actually move inside those bands:
- Services are the swing item - a full rewire and re-plumb can add £150–£250/sqm on its own, and 2026 labour pricing keeps electricians and plumbers the schedule’s critical path
- Kitchens and bathrooms price per room, not per metre - rental-grade kitchens £5k–£10k fitted, bathrooms £4k–£7k: multiply honestly on HMO-bound projects
- Condition is destiny - damp, roof, structural movement and non-standard construction belong in the budget before exchange, which is what surveys are for
- Spec discipline - price the exit’s spec: rental product to rental spec, resale product to local-ceiling spec - over-speccing is the quiet margin-killer
- Region moves everything - the same scope prices meaningfully differently between the South East and the North; use local quotes, not national averages
Light vs heavy refurbishment definition UK - the line lenders actually use
The light vs heavy refurbishment definition uk matters because it is a lending boundary, not a builder’s phrase. Light, to most lenders: no structural alterations, no planning permission required, works typically within roughly 15% of the property’s value - redecoration, new kitchen and bathroom, flooring, a non-structural reconfiguration. Heavy: anything structural, anything needing planning or building regulations sign-off, extensions, loft and basement conversions, change of use. The boundary decides product, pricing and process - light refurb bridges run faster with lighter monitoring; heavy schemes price higher, draw in stages and shade toward development finance territory, monitoring surveyor included. Misclassifying the project in your own head is how borrowers apply to the wrong lender and lose three weeks learning the definition.
BRRR strategy numbers UK - the worked example
The brrr strategy numbers uk investors actually need - buy, refurbish, refinance, rent - on an honest 2026 example.
The arithmetic, line by line:
- Buy - £140,000 tired terrace (bridging-funded; condition rules out a mortgage)
- Refurbish - 85 sqm light-to-medium scheme at ~£800/sqm = £68,000, plus 12% contingency ≈ £76,000 all-in
- Refinance - end value £265,000 on comparables; 75% BTL remortgage releases ~£198,750 (after the six-month rule window)
- Result - ~£216k deployed (price + works, before finance and buying costs) against ~£199k released: most capital recycled, equity and rent retained
- The honest caveats - down-valuation at refinance is the strategy’s real risk; finance costs and voids belong in the sheet; and the deal only works because the end value was evidenced before purchase
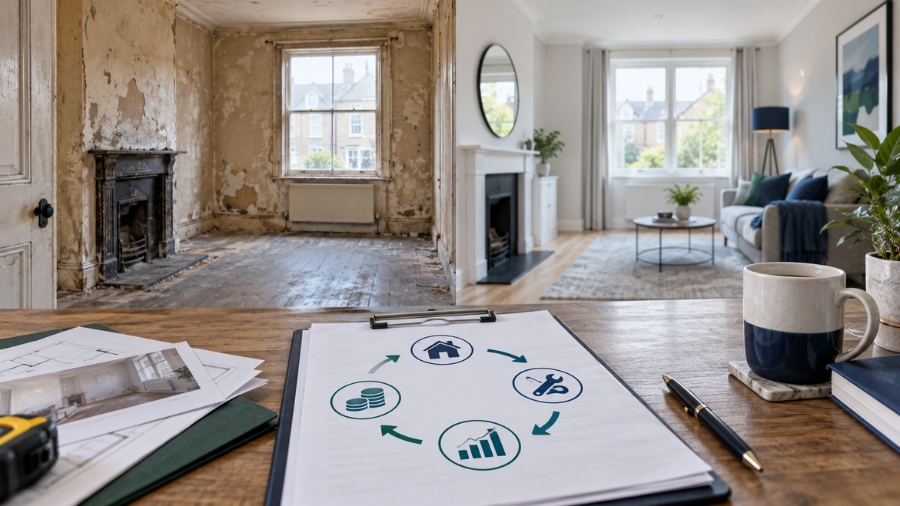
BRRR strategy numbers UK - the worked example, and the down-valuation risk that disciplines it.
The contingency rule - and the other lines amateurs forget
Professionals carry 10–15% contingency and expect to spend it - older stock hides its surprises inside walls, floors and roofs (lender expectations on this are covered in our contingency guide). The equally forgotten lines: finance costs (bridge interest and fees belong in the appraisal), utilities and council tax through the works, insurance for an empty property under renovation, skips and scaffold, and the schedule itself - every month late is a month of interest the brochure never mentioned. A budget without these is a wish with line items.
Funding the refurb - matching money to the works
The funding follows the definition: light schemes run on refurbishment bridging (often with a works facility inside it), heavy schemes on staged development-style money, and conversion-to-HMO projects on the bridge-to-HMO route; mechanics and pricing sit in our bridging costs guide. The broker’s job - Money Pilot’s job - is classifying the project the way lenders will, then placing it where that classification is welcome: 200+ lenders, zero broker fees, and the exit refinance mapped before the first skip arrives. Call 020 4634 8617 with the floor area and the scope.