✅ Which AI tools help small businesses manage finances?
The keepers cluster in four jobs: bookkeeping automation - receipt and invoice capture with AI coding inside the mainstream platforms (Xero, QuickBooks’ Intuit Assist, Sage Copilot, capture tools like Dext), typically saving hours weekly and cutting error rates; cash flow forecasting - tools that read your ledger and bank feed to project 13+ weeks ahead with scenario testing; credit control AI - automated, politely-escalating chasing that measurably cuts debtor days; and AI in lending - open-banking-fed underwriting that reads applicants in hours, which changes how you should present. Money Pilot pairs the tools with the funding - 200+ lenders, zero broker fees, FCA regulated (FRN: 968705).
Ai tools small business finance coverage splits into two genres: breathless demos, and the quieter reality of what owners actually keep paying for after month three. This guide is the second genre. The AI that survives contact with a real SME back office does three unglamorous jobs superbly - it reads paperwork, it predicts cash, and it chases money - and a fourth job is being done to you rather than by you: AI now reads your business when you apply to borrow. Here is what pays off, and how to be read well.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
AI bookkeeping software UK - the hours you stop spending
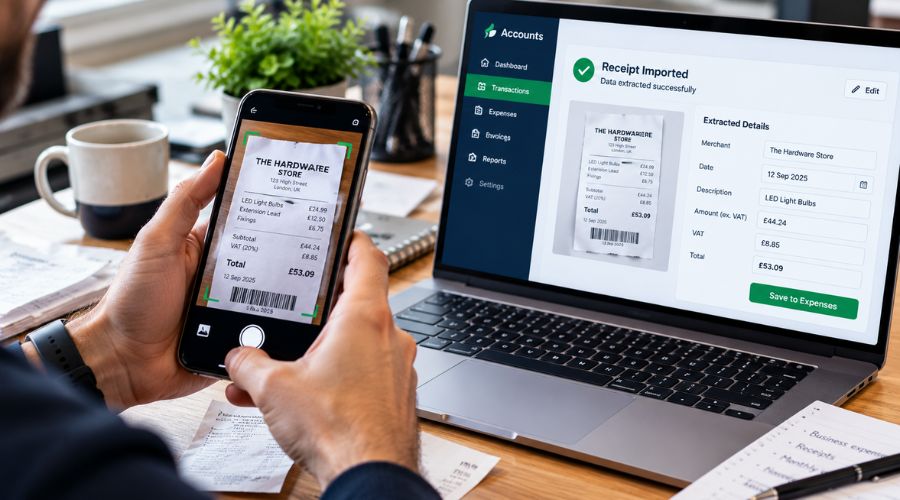
Ai bookkeeping software uk earns its subscription on one metric: minutes per transaction. The 2026 state of play - the mainstream platforms have absorbed the AI layer (Xero’s automation and analytics, QuickBooks with Intuit Assist, Sage Copilot), while capture specialists like Dext read receipts, invoices and statements, extract the data, propose the coding and learn your corrections. In practice that means photographed receipts posting themselves, supplier invoices arriving pre-coded, bank reconciliation reduced to approving suggestions, and VAT returns assembled from clean data - with Making Tax Digital’s expanding reach making digital records less optional every year. The honest caveats: AI coding is confidently wrong in predictable places (new suppliers, unusual items, director’s personal crossovers), so the winning setup is AI-does-the-typing, human-reviews-the-exceptions - and your accountant’s monthly hour moves from data entry to actual advice.
AI cash flow forecasting tools - the 13-week view without the spreadsheet grief
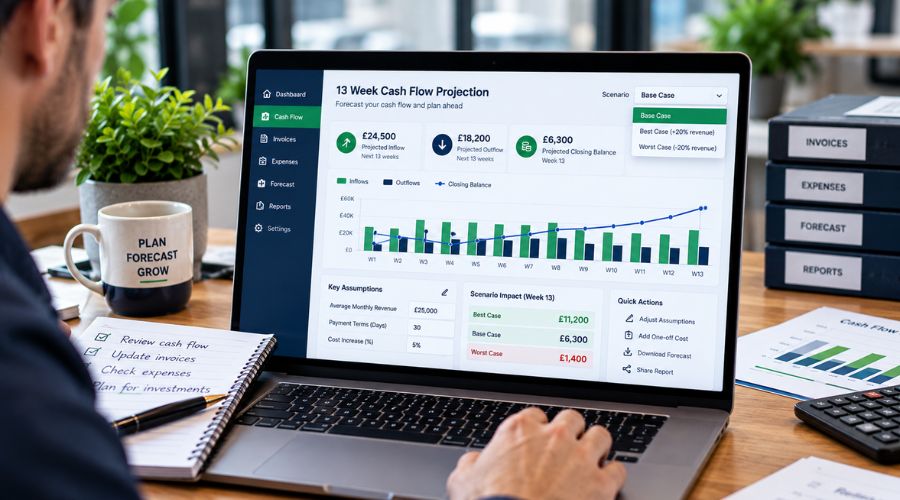
Ai cash flow forecasting tools attack the forecast most owners know they should maintain and don’t: connected to the ledger and bank feeds, they learn payment patterns per customer (not what terms say - what customers actually do), project balances weeks ahead, and let you scenario-test the decisions that matter: the hire, the VAT quarter, the big customer paying 20 days late. Platform-native analytics cover the basics; dedicated forecasting tools add scenario depth. Two uses justify the spend: early warning - a projected dip seen eight weeks out is a facility conversation, seen eight days out it’s a crisis (and the facility menu lives in our working capital guide and RCF explainer); and lender-grade evidence - a maintained, assumption-documented forecast is exactly what underwriters now ask for, and arriving with one changes the conversation.
AI in business lending UK - the algorithm reading your application
Ai in business lending uk is the shift most owners feel without seeing: the fintech lenders - and increasingly the banks - underwrite with models fed by open banking, filings and payment data, deciding in hours what committees took weeks over.
What it means for borrowers:
- Open banking is the new interview - models read 12+ months of real transactions: steady balances, controlled drawdowns and clean bounce-history outscore any brochure
- Speed cuts both ways - decisions in hours when the data fits the model; instant declines when it doesn’t, with no human to hear the story
- Hygiene is now pricing - messy personal/business crossovers, unexplained cash spikes and gambling-pattern flags genuinely move automated scores: run the accounts as if a model is watching, because one is
- The edge cases still need humans - seasonal businesses, recovery stories, complex structures: exactly where algorithmic lending declines well and a broker’s lender-matching wins
- Best of both - AI-tidy books and forecasts, human routing to the lender whose model (or underwriter) actually fits your shape
Credit control AI - the politest persistent chaser you’ll ever employ
The third payoff category automates the job nobody enjoys: AI credit control drafts and sends invoice chasing on escalating schedules, personalises tone by customer history, flags the accounts drifting toward trouble before they arrive, and - the measurable bit - cuts debtor days simply by never forgetting to follow up. Paired with the statutory rights and Fair Payment Code intelligence in our late payment guide, it professionalises collections without hiring for it; where the ledger gap persists anyway, invoice finance remains the structural answer AI only postpones.
The adoption playbook - and the honest limits
Adopt in payoff order: capture-and-bookkeeping first (fastest, cheapest win), forecasting second, credit-control automation third - one tool at a time, measured on hours saved and debtor days, cancelled without sentiment if the number disappoints. Keep the limits in view: AI doesn’t know your business is seasonal unless the data shows it, confidentially wrong coding compounds quietly without review, and no forecast tool replaces the judgement call of which funding to take - that pairing of machine-clean data with human lender-matching is precisely where Money Pilot sits: 200+ lenders, zero broker fees, and applications presented the way both algorithms and underwriters want to read them. Call 020 4634 8617. FCA regulated (FRN: 968705).