✅ Is student property still a good investment in the UK?
On the fundamentals, yes - student numbers remain at record levels, purpose-built supply has not kept pace, and well-located student HMOs continue to deliver gross yields in the 8 -12% territory that outruns standard lets. The honest caveats: Article 4 directions in most major student cities restrict creating new student HMOs (making existing licensed stock scarcer and more valuable), management is intensive, and city-level oversupply of PBSA can bite in weaker markets. Vehicle and city selection decide everything. Money Pilot finances both routes - 200+ lenders, zero broker fees, FCA regulated (FRN: 968705).
Student property investment uk runs on an enviable arithmetic problem: record student numbers chasing a supply of beds that planning policy actively restricts. That tension - demand that keeps growing, Article 4 directions that stop new student HMOs appearing in exactly the cities that need them - is simultaneously the sector’s moat and its entry barrier. In 2026 the investor’s real questions are three: is the demand durable, which vehicle (HMO or PBSA) earns the return, and can you still get in where Article 4 has pulled up the drawbridge.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
Student HMO demand 2026 UK - the numbers behind the moat
Student hmo demand 2026 uk rests on drivers that have proven stubbornly durable: domestic applications at or near record levels, international recruitment concentrated in exactly the Russell Group cities where housing is tightest, and a structural shortfall of beds - purpose-built development has never matched intake growth, leaving the traditional shared house carrying the load. The practical read-through for landlords: in strong university cities, well-run student HMOs let early (often the preceding autumn), in groups, on joint tenancies with guarantors - occupancy behaviour most asset classes can only envy. The same discipline applies as everywhere in HMO investing (our HMO strategy guide covers it): demand is city-specific, street-specific and spec-specific - a tired five-bed a bus ride from campus is not a moat, it is a void schedule.
PBSA vs student HMO returns UK - two vehicles, two businesses
The pbsa vs student hmo returns uk comparison is really a choice between owning a business and owning a unit in someone else’s. The student HMO: gross yields commonly 8 -12% (the full arithmetic in our HMO yield guide), direct control of asset and spec, conventional resale market - paid for with licensing, management intensity and Article 4 scarcity on the way in. PBSA units: hands-off income, professional management, headline net yields that look comparable - but bought with service charges and ground rents that move, a resale market largely limited to other investors, cash-only or specialist finance (mainstream BTL lenders broadly avoid individual PBSA units), and exposure to a single operator’s performance in a single scheme. The honest summary: HMOs reward operators, PBSA suits passive capital that has priced the exit constraints - and in cities where PBSA pipelines are heavy, the private HMO’s pricing power erodes first at the premium end.
Article 4 student cities map UK - the drawbridge explained
The article 4 student cities map uk is the sector’s defining constraint: directions that remove permitted development rights, so converting a family home (C3) to a small HMO (C4) needs full planning permission - routinely refused where “concentration” policies apply.
What investors must know:
- Where - most major student cities run Article 4 areas: Nottingham, Leeds, Manchester, Birmingham, Sheffield, Newcastle, Bristol, Southampton, Portsmouth, Leicester, Loughborough and more - boundaries are council-specific and move, so verify on the council’s own map before any offer
- What it does - stops new C4 conversions without planning; existing lawful HMOs keep their use (evidence it: licensing history, tenancy records, certificates of lawful use)
- The investment consequence - existing licensed student HMOs inside Article 4 zones carry scarcity value and often price above identical non-HMO houses; the “buy cheap and convert” play is largely dead inside the zones
- The diligence trap - buying a “student HMO” whose C4 use cannot be evidenced means buying a house that may never legally be one again
- Planning vs licensing - two separate regimes, both must be satisfied: our HMO licensing guide covers the second
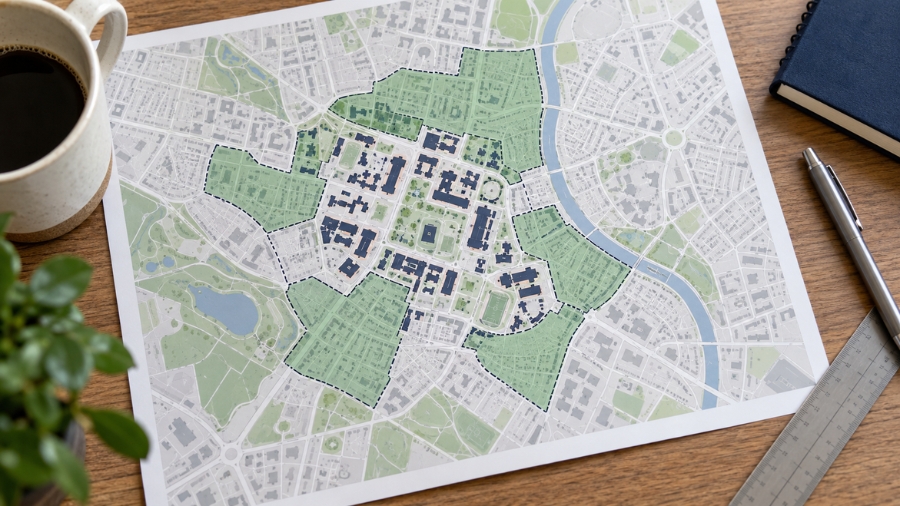
Article 4 student cities map UK — where the drawbridge is up, existing licensed stock is the asset.
The Renters’ Rights Act and student lets - the 2026 overlay
The Act’s move to periodic tenancies initially alarmed student landlords whose business runs on the academic calendar - the resolution worth knowing: a dedicated possession ground (Ground 4A) lets landlords of qualifying student HMOs recover possession ahead of each academic year, preserving the September cycle, while purpose-built student accommodation sits outside the regime via its own code. The compliance detail matters (notice periods, qualifying conditions), but the strategic read is reassuring: the student HMO model survived its biggest regulatory test intact — one more reason existing, compliant stock carries a premium.
Financing student property - and the 2026 playbook
Finance follows the vehicle. Student HMOs run through the specialist HMO market - lenders assessing aggregate room income, licensing and (for larger houses) 7-plus-bed criteria, with the specialist lender pool broker-routed; conversions outside Article 4 zones use the bridge-to-HMO route; PBSA units need cash or the small specialist corner that touches them. The 2026 playbook in one line: buy evidenced C4 use in Article 4 cities, buy the walk-to-campus street not the city average, spec for the group-booking market, and let scarcity - which planning policy keeps manufacturing - do the compounding. Money Pilot places all of it across 200+ lenders at zero broker fees: call 020 4634 8617. FCA regulated (FRN: 968705).