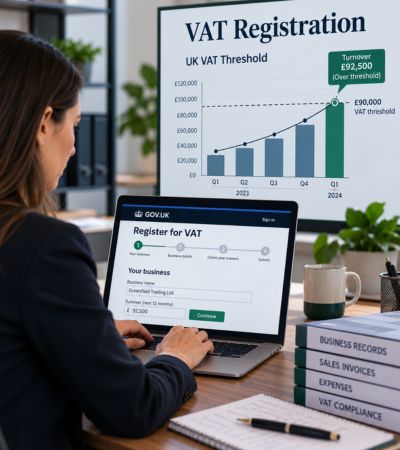
✅ When does a small business have to register for VAT?
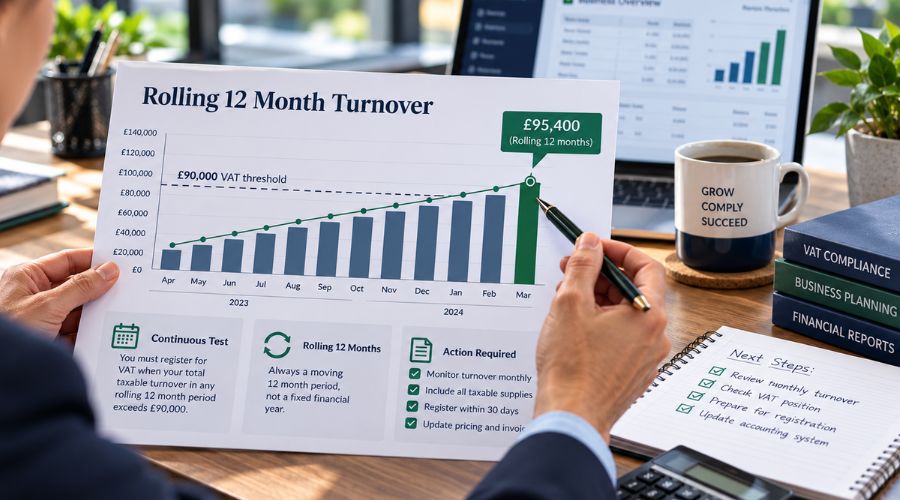
When taxable turnover passes £90,000 in any rolling 12-month period — checked month by month, not per accounting year — or when you expect to pass it in the next 30 days alone. You must register within 30 days of the month-end you crossed, with VAT charged from the effective date; late registration means paying VAT you never collected, plus penalties. Voluntary registration below the line can pay where customers are VAT-registered. Deregistration sits at £88,000. Money Pilot smooths the quarterly bill — 200+ lenders, zero broker fees, FCA regulated (FRN: 968705).
Every vat registration guide small business owners actually need starts with a correction: the £90,000 threshold is not measured against your accounting year — it is a rolling 12-month test, checked continuously, and missing the moment you cross it is the single most common VAT mistake in Britain. This guide covers the trigger rules, the scheme choices that change your cash flow, the first-return traps, and the funding move that stops a quarterly VAT bill from bullying an otherwise healthy business.
Bank of England held base rate at 4.25% in June 2026 - waiting for inflation to cool.
73% of UK SMEs expect to grow in the next 12 months - confidence remains strong.
VAT threshold UK explained — the rolling test that catches everyone
Vat threshold uk explained properly: at the end of every month, total your taxable turnover for the previous 12 months; the first time that figure exceeds £90,000, the clock starts — register within 30 days, effective from the first day of the second month after crossing. The companion test is forward-looking: if you expect taxable sales over £90,000 in the next 30 days alone (one big contract can do it), registration is immediate. The details that decide borderline cases:
- Taxable turnover means standard, reduced and zero-rated sales — zero-rated counts toward the threshold; exempt income (some rents, insurance, finance) does not
- Late discovery is expensive — HMRC treats you as registered from the date you should have been: VAT due on sales where you never charged it, out of your margin, plus a behaviour-based penalty
- The £88,000 deregistration line gives hovering businesses a corridor — but deliberately suppressing growth to stay under (“bunching”) is a strategy with a ceiling, and artificial business-splitting is a well-litigated HMRC target
- Voluntary registration below the line pays when your customers are VAT-registered businesses (they reclaim what you charge) and you have input VAT to recover — and costs margin when you sell to the public
- Pre-registration reclaim — on registering you can recover VAT on goods still on hand bought up to 4 years back, and services up to 6 months: keep the invoices
Flat rate scheme worth it UK — and the other schemes that move cash
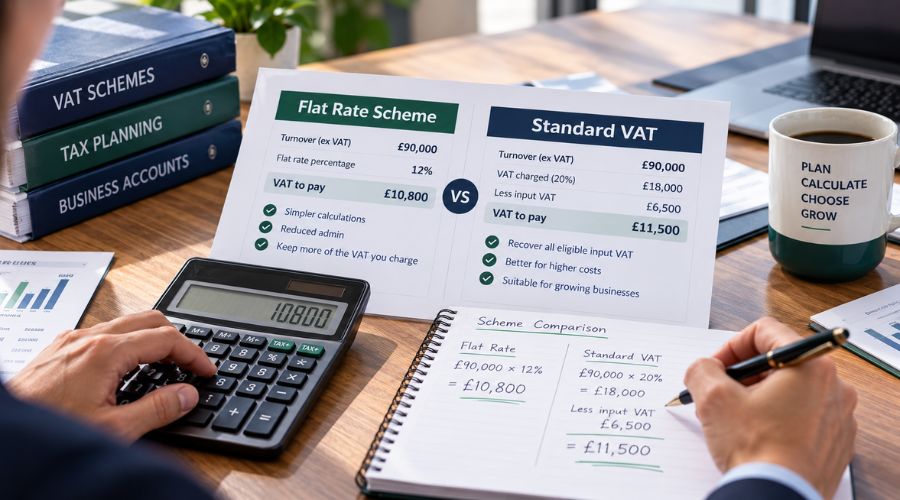
Is the flat rate scheme worth it uk businesses ask — answer: it depends almost entirely on your inputs. The FRS (join up to £150,000 taxable turnover ex-VAT) swaps input-VAT recovery for a flat percentage of gross takings by sector, with a 1% first-year discount — brilliant simplification for low-cost service businesses, a quiet money-loser since the limited cost trader rule forces businesses spending little on goods onto 16.5%, which recovers almost nothing. Run the arithmetic both ways before choosing. The schemes that help cash flow more reliably: Cash Accounting (to £1.35m) — you pay HMRC only when customers pay you, the natural choice for anyone fighting the late-payment culture in our late payment guide; and Annual Accounting — one return, instalments through the year, for owners who prefer predictability to quarterly adrenaline.
First VAT return mistakes UK — the five that cost real money
First vat return mistakes uk advisers see on repeat — every one avoidable with an hour of setup.
The repeat offenders:
- Missing the MTD plumbing — VAT returns file through Making Tax Digital software with digital records; spreadsheets alone don’t comply, and the AI bookkeeping stack makes compliance the easy path
- Claiming blocked input VAT — client entertainment and most car purchases are classic disallowed claims that invite review
- Forgetting the pre-registration reclaim — the 4-year goods / 6-month services recovery is free money left on tables every quarter
- Wrong rates on edge cases — zero-rated vs exempt vs standard on food, construction, exports: classification errors compound every return
- No cash discipline for the bill — VAT collected is HMRC’s money resting in your account; businesses that sweep it to a separate pot never meet the quarterly panic
- The penalty frame — late returns earn points and points earn fines, late payment accrues interest fast: file on time even when paying is hard, then fund the gap properly
When the quarterly bill bites — funding VAT properly
A growing business can be profitable on paper and still meet a VAT quarter with the cash sitting in unpaid invoices — the classic timing squeeze. The structural answers, in order of preference: cash accounting so the liability tracks receipts; a swept VAT pot so the money was never “yours”; and where timing still bites, VAT funding — short-term facilities that spread a quarterly bill over 3–12 months, keeping HMRC paid on time and working capital in the business, alongside the broader working-capital menu and invoice finance where debtor days are the real culprit. Money Pilot arranges VAT and tax funding across 200+ lenders at zero broker fees — the full picture sits on our VAT and tax funding guide. Call 020 4634 8617 before the quarter does the calling. FCA regulated (FRN: 968705).